
Simple Investment Calculator
Simple investment calculator: find what a lump sum grows to at a set rate and compounding schedule, or the amount, rate or contribution a target needs.
Written by
Annie Button
Updated
There was an error with your calculation.
FUTURE ACCOUNT VALUE
$34,186.76
Simple investment calculator at a glance#
What does the simple investment calculator do?#
It shows what one sum of money grows to after a number of years at a fixed rate, with interest added on the schedule you pick. A second tab works backward from a goal: how much to invest today, what rate you'd need, or what regular top-up closes the gap.
How much will $10,000 be worth in 10 years at 6%?#
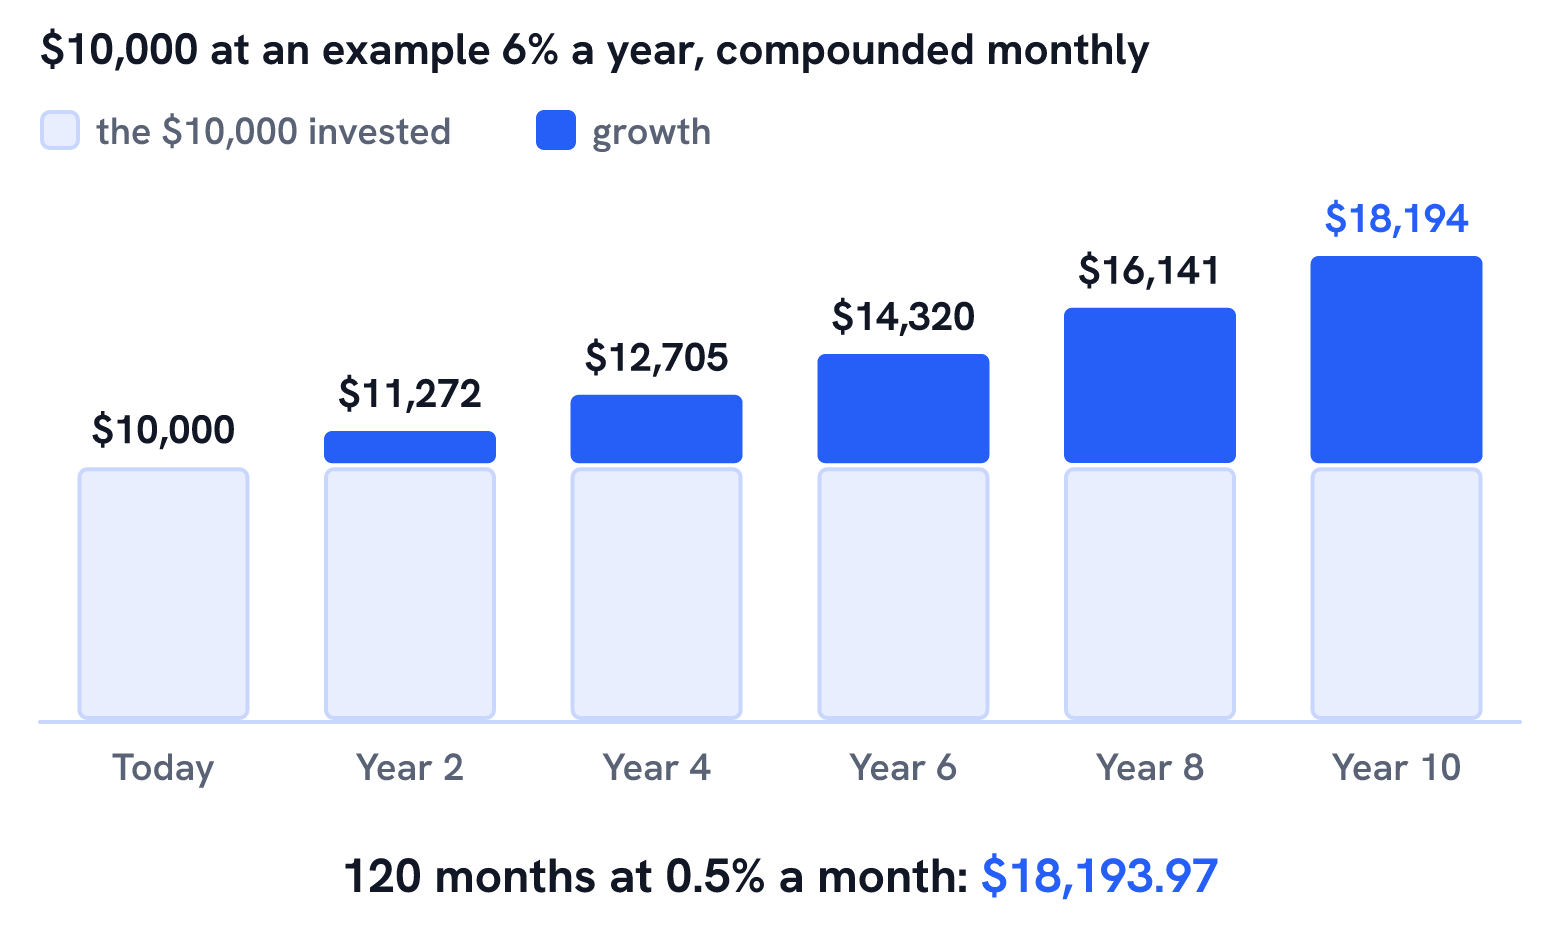
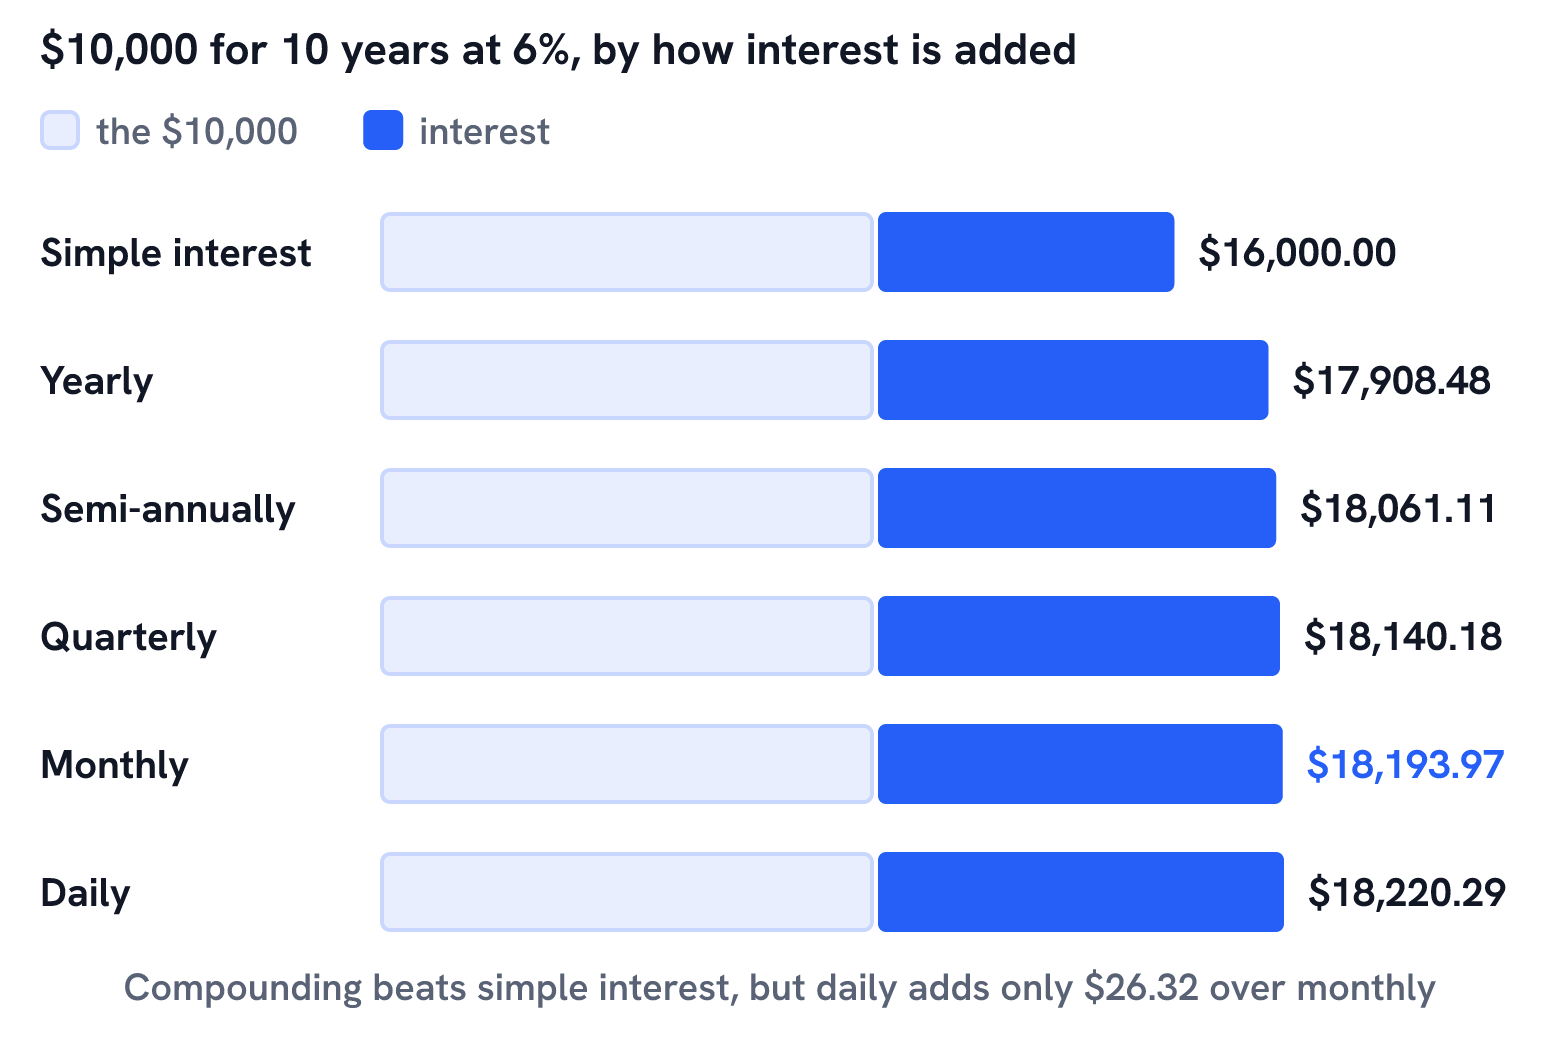
At an example 6% a year compounded monthly, it's $18,193.97. With interest added once a year it's $17,908.48. Either way, the growth is close to $8,000 on top of the $10,000.
Is this simple interest or compound interest?#
Compound interest, despite the name. Simple interest on $10,000 at 6% for 10 years is $600 a year, $6,000 in all, for a total of $16,000. Compounded monthly, the same money reaches $18,193.97, because each month's interest earns interest after that. The simple interest calculator handles the flat version.
How a lump sum grows#
A lump sum is money invested once and left alone. Each compounding period adds interest to the balance, and the next period pays interest on that bigger balance. OpenStax Principles of Finance gives the yearly version as FV = PV × (1 + r)n.
When interest is added m times a year, divide the yearly rate by m and multiply the years by m. At 6% compounded monthly, that's 0.5% a month for 120 months:
$10,000 × 1.005120 = $10,000 × 1.819397 = $18,193.97
Growth starts slow and speeds up. The first two years add $1,271.60, the last two add $2,052.54, with no new money going in.
At 6% compounded monthly the $10,000 doubles in about 11.6 years, and the compound interest calculator page explains the Rule of 72 for estimating doubling time at any rate.
The calculator applies one steady rate for the whole period. A savings account or CD rate can be fixed, but investment returns rise and fall, so read the result as what happens if that rate holds. This gives an estimate, not financial advice.
Using the Future Simple tab#
For a lump sum, enter the investment, the number of years and the yearly interest rate, pick how often interest compounds, and set Contributions to 0. The result is the Future Account Value: $18,193.97 for the example above with Compound on Monthly (APR).
The rate has to be above zero. The Compound menu runs from daily to semi-annually and has no yearly option, so for interest added once a year use the formula, or the future value calculator with 10 periods at 6%, which gives $17,908.48.
How often interest compounds#
The more often interest is added, the more you end up with, but the gains shrink fast. Here is $10,000 for 10 years at 6% six ways.
Working backward: the Target Value tab#
The Target Value tab starts from the amount you want and solves for one missing piece. With a $20,000 goal in 10 years at an example 6% compounded monthly:
- Required Investment Amount: invest $10,992.65 today. That's $20,000 ÷ 1.005120.
- Required Interest Rate: turning $10,000 into $20,000 in 10 years takes 6.95% a year, compounded monthly.
- Required Contributions: $10,000 today grows to $18,193.97 on its own, so the last $1,806.03 needs $11.02 a month.
For a plan built mainly on monthly deposits, the investment calculator adds deposit timing, yearly or monthly contributions and a full schedule.
Return on a lump sum#
A simple return on investment compares the gain with what you put in: (end value − amount invested) ÷ amount invested × 100. For the example, ($18,193.97 − $10,000) ÷ $10,000 = 81.94% over 10 years. The calculator shows the end value, so this last step is by hand, and the percentage calculator can help with it.
What a lump sum grows to#
Balances at an example 6% a year, compounded monthly, with nothing added after the first deposit.
| Invested Today | After 5 Years | After 10 Years | After 20 Years | After 30 Years |
|---|---|---|---|---|
| $1,000 | $1,348.85 | $1,819.40 | $3,310.20 | $6,022.58 |
| $5,000 | $6,744.25 | $9,096.98 | $16,551.02 | $30,112.88 |
| $10,000 | $13,488.50 | $18,193.97 | $33,102.04 | $60,225.75 |
| $25,000 | $33,721.25 | $45,484.92 | $82,755.11 | $150,564.38 |
| $50,000 | $67,442.51 | $90,969.84 | $165,510.22 | $301,128.76 |
Sources#
- OpenStax, Principles of Finance, 7.2 Time Value of Money (TVM) Basics (future value of a single amount)
- Investor.gov (U.S. Securities and Exchange Commission), What is compound interest? (with the Rule of 72)
Frequently asked questions#
How long does it take to double $10,000 at 6%?#
About 12 years by the Rule of 72 (72 ÷ 6). With monthly compounding the exact time is 11.6 years, and with interest added once a year it's 11.9 years.
What is the formula for a lump sum investment?#
FV = PV × (1 + r ÷ m)k, where r is the yearly rate as a decimal, m is the number of compounding periods a year and k is m times the number of years. For $10,000 at 6% compounded monthly for 10 years, that's $10,000 × 1.005120 = $18,193.97.
How much do I need to invest now to have $20,000 in 10 years?#
At an example 6% a year compounded monthly, $10,992.65. Divide the goal by the growth factor: $20,000 ÷ 1.819397. The Required Investment Amount option on the Target Value tab does it for you.
How do I work out the return on investment?#
Subtract what you invested from the end value, divide by what you invested and multiply by 100. $10,000 growing to $18,193.97 is an 81.94% return: ($18,193.97 − $10,000) ÷ $10,000 × 100 = 81.94%. The calculator shows the end value, so this step is by hand.
Can I add regular contributions?#
Yes. Enter an amount in Contributions and pick how often it goes in. Each contribution goes in at the end of its period. For more control over timing and for solving the time needed, use the investment calculator.
Related calculators
View all calculators Auto Loan CalculatorAuto loan calculator: estimate your monthly car payment, total interest and total cost from price, down payment, trade-in, sales tax, fees, rate and term.
 Business Loan CalculatorBusiness loan calculator: estimate the payment, total interest and real rate (APR) of a small business loan with fees, paid monthly, weekly or quarterly.
 Compound Interest CalculatorCompound interest calculator: find the balance, principal, rate or time for any compounding period from yearly to continuous, with worked examples.
 Future Value CalculatorFuture value calculator: find what a starting amount plus regular deposits will be worth after any number of periods, with deposits at the start or end.
 Interest CalculatorInterest calculator: see how money grows with monthly compounding, regular additions, tax and inflation, plus simple vs compound interest examples.
 Investment CalculatorInvestment calculator: see what a starting amount plus monthly or yearly contributions grows to, or solve for the contribution, rate or time needed.