401K Calculator
401k calculator: project your 401(k) balance at retirement from your salary, contribution, employer match, raises and return, plus the monthly payout.
Written by
Annie Button
Updated
Preview 401K Calculator Widget
There was an error with your calculation.
Result
At the retirement age of 65, the 401(k) balance will be $1,537,963, which is equivalent to $546,566 in purchasing power today.
Self Contributions
Employer Match
Interest
| Total contributions | $516,720 |
|---|---|
| Employee contributions | $453,235 |
| Employer match | $63,485 |
| Total interest | $1,021,243 |
| Total payouts | $2,644,426 |
| Withdrawing monthly | $11,018 per month can be withdrawn in retirement until 85. At 65, this is equivalent to $3,916 in purchasing power today, and at 85, is equivalent to $2,168. |
| Withdrawing annually | $134,087 per year can be withdrawn in retirement until 85. At 65, this is equivalent to $47,652 in purchasing power today, and at 85, is equivalent to $26,384. |
401(k) calculator at a glance#
How much will my 401(k) be worth at retirement?#
It depends on what goes in, for how long and at what return. Starting at 30 with $0, putting 6% of a $60,000 salary in each year with a 50% employer match on the first 6%, 3% yearly raises and an example 6% return, the calculator projects $877,000 at 65. Growth is $550,505 of that.
How much should I contribute to my 401(k)?#
There's no single right percentage, but two numbers frame it: your plan's match limit and the IRS limit. Contributing up to the match limit collects all the employer money on offer. With a 50% match on the first 6% of a $60,000 salary, 3% brings in $900 of match a year and 6% brings in $1,800. For 2026 the IRS caps your own deferrals at $24,500, or more with catch-up contributions if you're 50 or older and your plan allows them.
What is the 401(k) contribution limit for 2026?#
The IRS limit on your own 401(k) contributions is $24,500 for 2026, up from $23,500 for 2025. If you're 50 or older and your plan permits it, you can add a catch-up of $8,000, or $11,250 if you turn 60 to 63 during the year. Your deferrals and your employer's contributions together count toward an overall limit of $72,000 or 100% of your pay, whichever is less, not counting catch-up contributions.
How the 401(k) calculator works#
You enter your age, salary, current 401(k) balance, contribution as a percent of salary, the employer match and its limit, your retirement age and life expectancy, an annual return, an inflation rate and a yearly salary increase.
The calculator then works in whole years. Each year it adds three things to the balance:
- the return on the balance at the start of the year
- your contribution: salary × your contribution percent
- the match: salary × the smaller of your percent and the match limit × the match percent
Then it raises the salary by the increase you entered and repeats until your retirement age. The growth formula behind each year is the same compound growth the future value calculator teaches step by step.
How an employer match works#
A match is money your employer adds when you contribute. The IRS 401(k) Plan Overview gives this example: the employer contributes 50 cents for each dollar you defer. A match can also be capped at a share of your pay, which is what the Emp. Match Limit field is for.
With a 50% match on the first 6% of a $60,000 salary:
- You put in 3% ($1,800), the match is $900.
- You put in 6% ($3,600), the match is $1,800.
- You put in 10% ($6,000), the match is still $1,800.
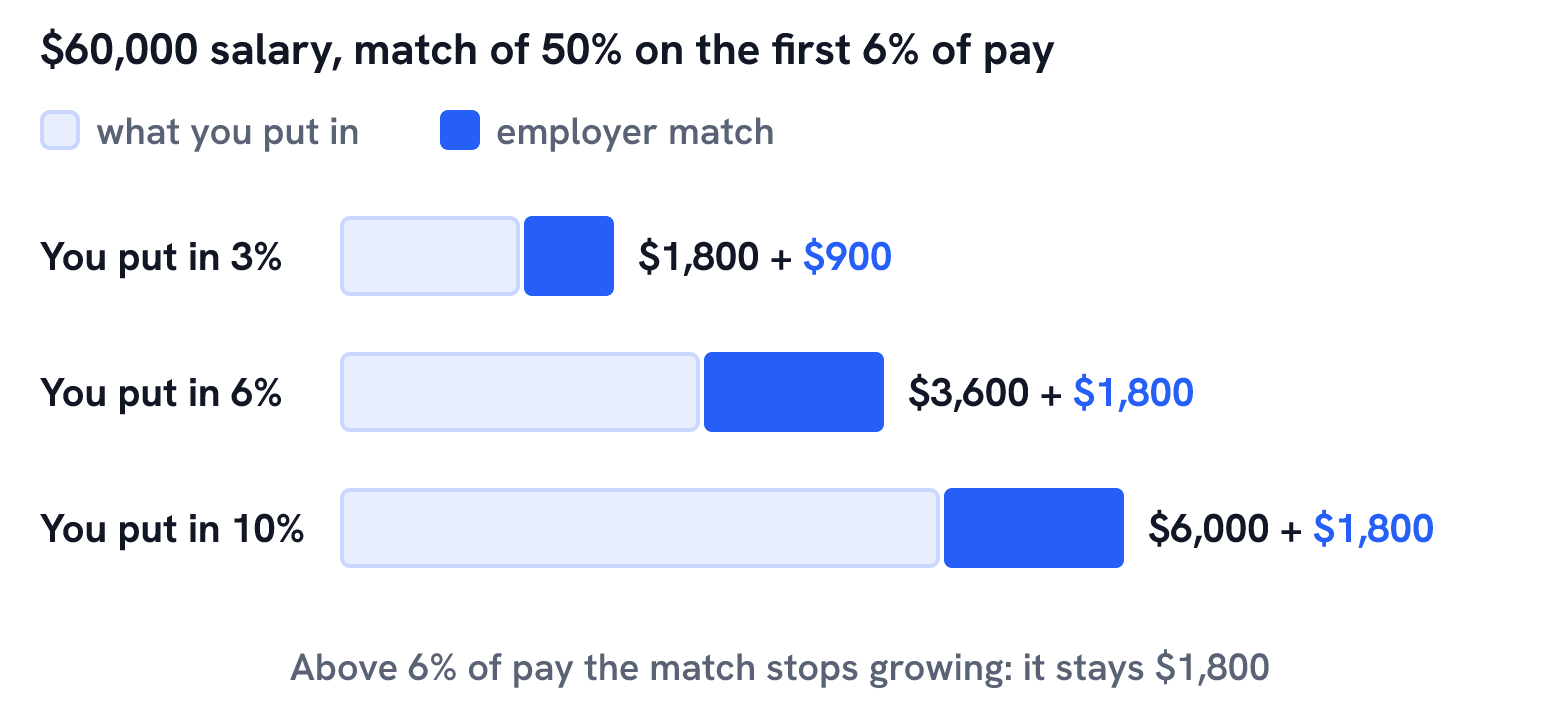
With this formula, every extra 1% of pay you put in below the limit brings another 0.5% from your employer. Above it, the match stays where it is. Your plan's match formula may be different, so check your plan documents and enter its numbers.
Worked example: from 30 to 65#
Enter age 30, salary $60,000, balance $0, contribution 6%, employer match 50% with a 6% limit, retirement at 65, life expectancy 85, an example annual return of 6%, inflation 3% and salary increases of 3%. The calculator shows:
- Balance at 65: $877,000
- Your contributions: $217,663
- Employer match: $108,832
- Growth: $550,505
- At today's prices (purchasing power): $311,671
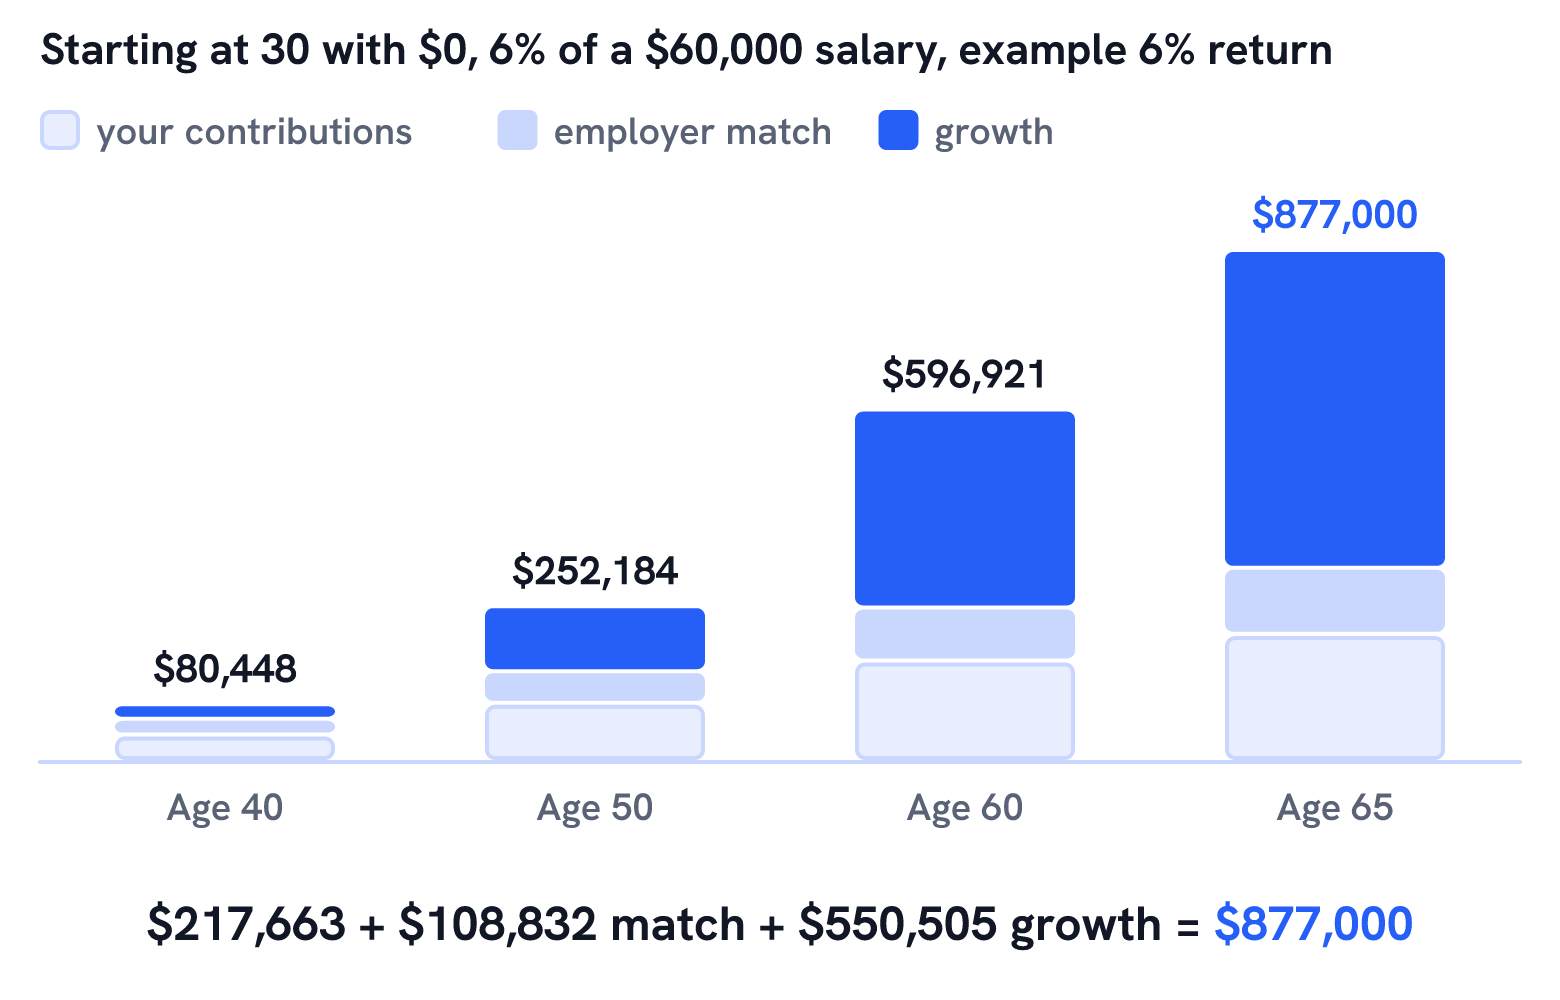
Growth overtakes your own contributions at about age 49 and makes up 63% of the final balance, because the early contributions compound for more than 30 years. Contributing 3% instead of 6% halves the projection to $438,500, since both your money and the match drop by half. Contributing 10% raises it to $1,266,778, with no extra match.
The return you enter drives the result more than anything else. At an example 4% the same plan reaches $611,402, at 8% it reaches $1,292,920. Real returns vary from year to year and the projection assumes a steady rate. This gives an estimate, not financial advice.
The payout: what the balance pays in retirement#
The calculator also turns the balance into an income. It works out the level monthly withdrawal that would run the balance down to zero by your life expectancy if the rest kept earning the same return. In the example, $877,000 at 65 supports $6,283 a month until 85. Taken once a year instead, the calculator shows $76,461 a year.
It shows that income at today's prices too, using your inflation rate: $6,283 a month at 65 buys what $2,233 buys today with 3% inflation. A fixed withdrawal also loses buying power each year of retirement. The retirement calculator page explains the 4% rule and other ways to plan withdrawals.
2026 401(k) contribution limits#
The IRS sets these limits each year. The figures below are for traditional and safe harbor 401(k) plans in tax year 2026, from the IRS announcement of November 13, 2025 and the IRS contribution limits page. SIMPLE 401(k) plans have lower limits. Catch-up contributions are available if your plan permits them, and eligibility goes by your age at the end of the calendar year.
| Who | Your Own Contributions, 2026 |
|---|---|
| Under 50 | $24,500 |
| 50–59, or 64 and older | $32,500 ($24,500 + $8,000 catch-up) |
| Turning 60–63 during the year | $35,750 ($24,500 + $11,250 catch-up) |
The overall limit on everything added to your account in 2026 (your deferrals, employer matching and other employer contributions, not counting catch-up) is the lesser of 100% of your pay or $72,000.
What percentage of salary reaches the limit#
The calculator doesn't stop at the IRS limit, so a high contribution percent on a high salary can project more than the law allows. This table shows the percent of salary that reaches the 2026 limit.
| Salary | Under 50 ($24,500) | 50 to 59, or 64 and Older ($32,500) | 60 to 63 ($35,750) |
|---|---|---|---|
| $50,000 | 49.00% | 65.00% | 71.50% |
| $60,000 | 40.83% | 54.17% | 59.58% |
| $75,000 | 32.67% | 43.33% | 47.67% |
| $100,000 | 24.50% | 32.50% | 35.75% |
| $150,000 | 16.33% | 21.67% | 23.83% |
| $200,000 | 12.25% | 16.25% | 17.88% |
What the calculator leaves out#
- The IRS limits and catch-up contributions: enter a percent that stays within them.
- Taxes: traditional 401(k) deferrals generally aren't subject to federal income tax withholding when you make them, and the IRS says deferrals and investment gains aren't subject to federal income tax until they're distributed. Social Security and Medicare taxes still apply to your deferrals. So the payout figures are before income tax. Roth 401(k) contributions follow different rules.
- Fees, which lower the return you actually keep.
- Changes in the match, gaps in work, and raises that differ from year to year.
Sources#
- IRS, 401(k) limit increases to $24,500 for 2026, IRA limit increases to $7,500 (IR-2025-111, November 13, 2025)
- IRS, Retirement topics: 401(k) and profit-sharing plan contribution limits
- IRS, 401(k) Resource Guide: Plan Participants, 401(k) Plan Overview
Frequently asked questions#
Does the employer match count toward the $24,500 limit?#
No. The $24,500 limit for 2026 applies to your own elective deferrals. Your deferrals and your employer's contributions together count toward an overall limit of $72,000 or 100% of your pay, whichever is less, not counting catch-up contributions.
What is the 401(k) catch-up contribution for 2026?#
It's $8,000 if you're 50 or older by the end of the year and your plan permits catch-up contributions, for a personal total of $32,500. If you turn 60, 61, 62 or 63 during the year, the catch-up is $11,250 instead, for $35,750.
Is the 401(k) payout before or after tax?#
Before. With a traditional 401(k), deferrals and investment gains aren't subject to federal income tax until they're distributed, so your take-home income in retirement can be lower than the payout shown.
What return rate should I enter?#
Use a few examples rather than one guess. With the worked example, an example 4% gives $611,402 at 65, 6% gives $877,000 and 8% gives $1,292,920. Investment returns aren't guaranteed and change from year to year.
How much is 6% of my salary?#
Multiply your salary by 0.06. On $60,000 that's $3,600 a year, or $300 a month. The salary calculator converts yearly pay into monthly, biweekly or weekly amounts.
Why does the calculator show purchasing power?#
Prices rise over 35 years. With 3% inflation, $877,000 at 65 buys what $311,671 buys today. The inflation rate you enter only changes the purchasing power figures, not the balance.
Related calculators
View all calculators Future Value CalculatorFuture value calculator: find what a starting amount plus regular deposits will be worth after any number of periods, with deposits at the start or end.
 Interest CalculatorInterest calculator: see how money grows with monthly compounding, regular additions, tax and inflation, plus simple vs compound interest examples.
 Investment CalculatorInvestment calculator: see what a starting amount plus monthly or yearly contributions grows to, or solve for the contribution, rate or time needed.
 Loan CalculatorLoan calculator: get the monthly payment, total interest and amortization schedule for any loan amount, rate and term, with a payment table by amount.
 Mortgage CalculatorMortgage calculator: estimate principal and interest from price, down payment, rate and term, with taxes, insurance, PMI and HOA in the total cost.
 Mortgage Payment CalculatorMortgage payment calculator: find the monthly principal and interest payment and see how an extra monthly payment shortens the loan and cuts interest.