
Future Value Calculator
Future value calculator: find what a starting amount plus regular deposits will be worth after any number of periods, with deposits at the start or end.
Written by
Alize Mendez
Updated
There was an error with your calculation.
Future Value
Future Value: $39,869.90
PV (Present Value): $12,431.62
N (Number of Periods): 20
I/Y (Interest Rate): 6
PMT (Periodic Deposit): $200.00
Starting Amount: $10,000.00
Total Periodic Deposits: $4,000.00
Total Interest: $25,869.90
Starting amount
Periodic deposits
Interest
| № | BEGINNING BALANCE | DEPOSIT | INTEREST | ENDING BALANCE |
|---|---|---|---|---|
| 1 | $10,200.00 | $200.00 | $612.00 | $10,812.00 |
| 2 | $11,012.00 | $200.00 | $660.72 | $11,672.72 |
| 3 | $11,872.72 | $200.00 | $712.36 | $12,585.08 |
| 4 | $12,785.08 | $200.00 | $767.10 | $13,552.19 |
| 5 | $13,752.19 | $200.00 | $825.13 | $14,577.32 |
| 6 | $14,777.32 | $200.00 | $886.64 | $15,663.96 |
| 7 | $15,863.96 | $200.00 | $951.84 | $16,815.80 |
| 8 | $17,015.80 | $200.00 | $1,020.95 | $18,036.74 |
| 9 | $18,236.74 | $200.00 | $1,094.20 | $19,330.95 |
| 10 | $19,530.95 | $200.00 | $1,171.86 | $20,702.81 |
| 11 | $20,902.81 | $200.00 | $1,254.17 | $22,156.97 |
| 12 | $22,356.97 | $200.00 | $1,341.42 | $23,698.39 |
| 13 | $23,898.39 | $200.00 | $1,433.90 | $25,332.30 |
| 14 | $25,532.30 | $200.00 | $1,531.94 | $27,064.23 |
| 15 | $27,264.23 | $200.00 | $1,635.85 | $28,900.09 |
| 16 | $29,100.09 | $200.00 | $1,746.01 | $30,846.09 |
| 17 | $31,046.09 | $200.00 | $1,862.77 | $32,908.86 |
| 18 | $33,108.86 | $200.00 | $1,986.53 | $35,095.39 |
| 19 | $35,295.39 | $200.00 | $2,117.72 | $37,413.11 |
| 20 | $37,613.11 | $200.00 | $2,256.79 | $39,869.90 |
Future value calculator at a glance#
What is future value?#
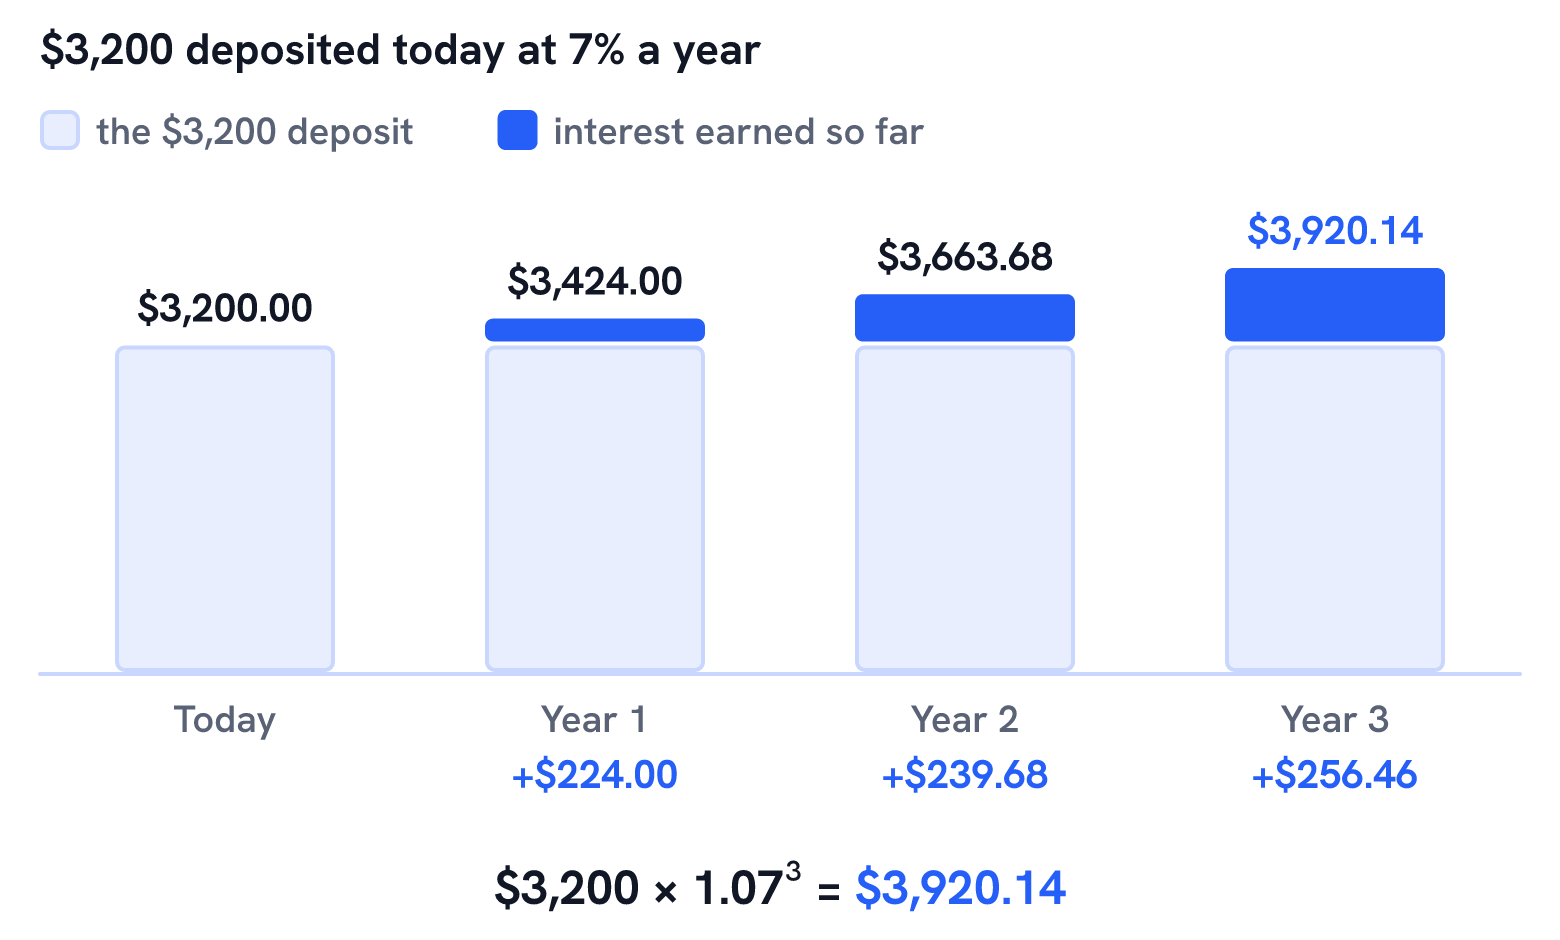
Future value is what money you have now, or a series of deposits, will be worth at a later date once interest is added. A deposit of $3,200 earning 7% a year is worth $3,920.14 three years from now. The calculator above works it out from four inputs: the present value, the interest rate per period, the number of periods and any regular deposit.
What is the future value of an annual deposit of $800 earning 6% for 15 years?#
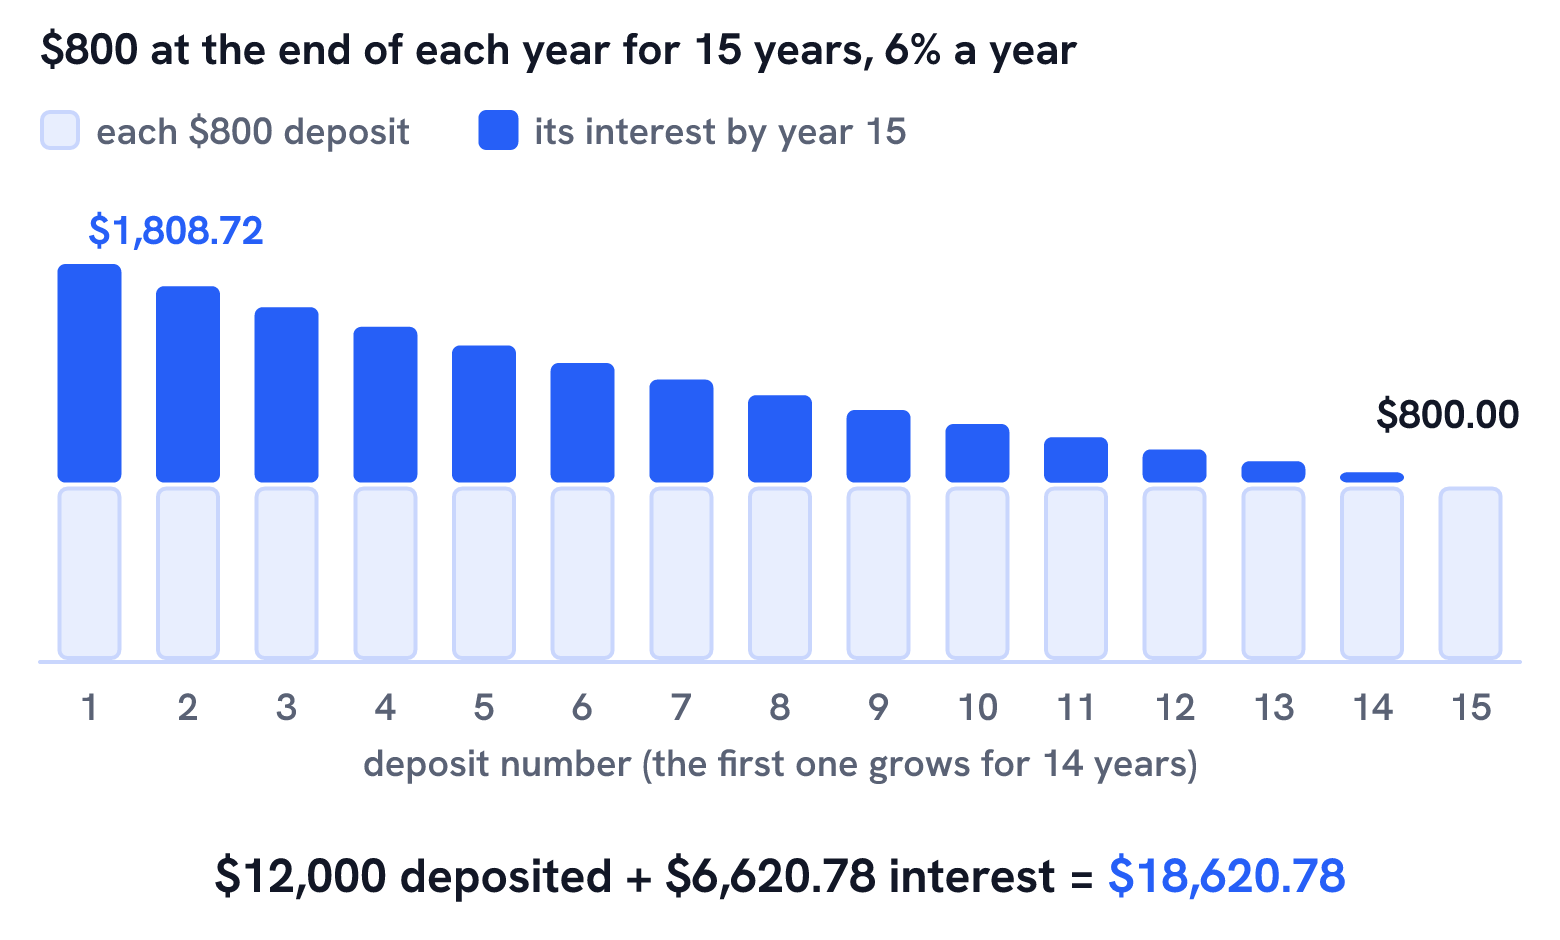
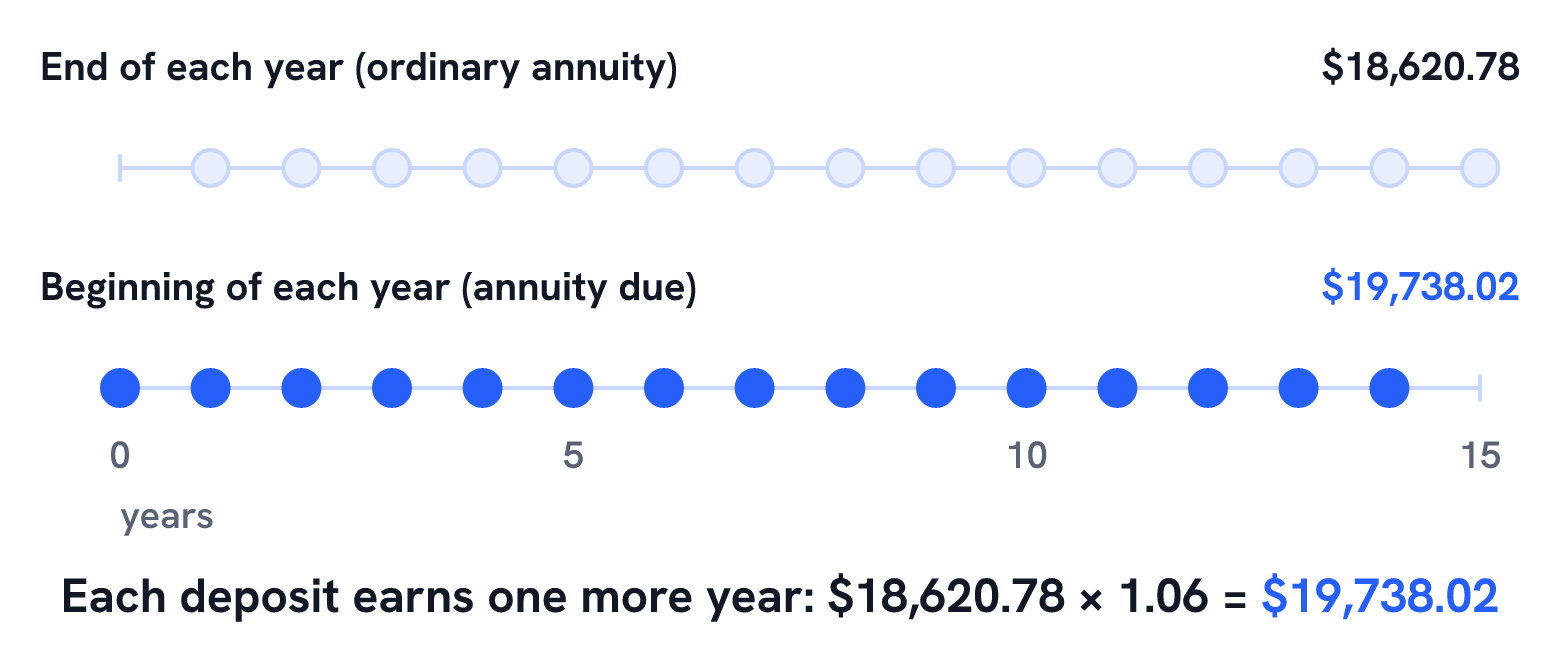
It's $18,620.78 if each $800 goes in at the end of the year. You deposit $12,000 in total and interest adds $6,620.78. If each deposit goes in at the start of the year instead, the answer is $19,738.02.
What is the formula for future value?#
For one deposit, FV = PV × (1 + r)n, where r is the rate per period as a decimal and n is the number of periods. For equal deposits at the end of each period, FV = PMT × ((1 + r)n − 1) ÷ r. When you have a starting amount and deposits, add the two results.
How future value works#
Money left to earn interest grows, and with compound interest the interest earns interest too. The SEC's Investor.gov shows it with $100 at 5% a year: $105 after the first year and $110.25 after the second, because the second year pays 5% on the $5 of interest as well. Future value is that process carried forward for as many periods as you need.
Three numbers set the answer: what you start with, the rate per period and how many periods the money stays in. A higher rate or a longer time both raise the result, and the gain speeds up the longer the money stays, which is why each year adds more than the year before.
The calculator assumes the same rate every period. Savings rates change and investment returns rise and fall, so read the result as what happens if the rate holds. This gives an estimate, not financial advice.
Future value of a lump sum#
A lump sum is a single deposit made today with nothing added later. Multiply it by 1 plus the rate once for every period. OpenStax Principles of Finance writes it as FV = PV × (1 + r)n.
Take $3,200 deposited today at 7% a year for 3 years:
- Year 1: $3,200 × 1.07 = $3,424.00
- Year 2: $3,424.00 × 1.07 = $3,663.68
- Year 3: $3,663.68 × 1.07 = $3,920.14
In one step, $3,200 × 1.073 = $3,200 × 1.225043 = $3,920.14. The interest is $224.00 in the first year, $239.68 in the second and $256.46 in the third. Each year earns more because the 7% now applies to the earlier interest too.
To check it in the calculator, enter 3200 as the present value, 7 as the interest rate, 3 as the periods and 0 as the periodic deposit. It shows a future value of $3,920.14 and total interest of $720.14. The compound interest calculator runs the same growth and can also solve for the rate or the time.
Future value of an annuity (regular deposits)#
An annuity is a series of equal deposits made at regular intervals. Each deposit grows for a different length of time: the first for the longest, the last hardly at all. You could grow each one separately and add them up. The annuity formula does that in one step:
FV = PMT × ((1 + r)n − 1) ÷ r
For $800 at the end of each year for 15 years at 6%:
- 1.0615 = 2.396558
- (2.396558 − 1) ÷ 0.06 = 23.275970
- $800 × 23.275970 = $18,620.78
The first deposit sits for 14 years and becomes $1,808.72. The fifteenth arrives at the very end and stays at $800.00. All fifteen together come to $18,620.78, which is $12,000 of deposits plus $6,620.78 of interest.
The calculator needs a present value above zero, so it can't take a deposits-only problem exactly. Enter 0.01 as the present value, 800 as the periodic deposit, 6 as the rate and 15 as the periods, then switch the payment timing to End. It shows $18,620.80, two cents high because that extra cent also grows for 15 years. For an exact textbook answer, use the formula.
Deposits at the beginning or end of each period#
Deposits at the end of each period make an ordinary annuity. Deposits at the start make an annuity due, and every deposit earns one extra period of interest. The OpenStax rule is to work it out as an ordinary annuity, then multiply by (1 + r) one more time:
$18,620.78 × 1.06 = $19,738.02
The formula above and the $18,620.78 answer assume deposits at the end of each period. The calculator's Periodic Payment switch starts on Beginning, so switch it to End to match an end-of-period problem.
A starting amount plus deposits#
Many plans have both: money already saved and a deposit every period. The future value is the two parts added together, and that's what the calculator computes when you fill in every field. Take $3,200 today plus $800 at the end of each year at 7% for 3 years:
- Starting amount: $3,200 × 1.073 = $3,920.14
- Deposits: $800 × ((1.073 − 1) ÷ 0.07) = $2,571.92
- Future value: $3,920.14 + $2,571.92 = $6,492.06
Next to the future value, the calculator lists a PV line. It's the final balance discounted back to today at the same rate, $6,492.06 ÷ 1.073 = $5,299.45, the one deposit today that would grow to the same amount. Below that come the total deposits, the total interest, a chart of the three parts and a period-by-period schedule.
Monthly, quarterly and other periods#
The calculator works in periods, not years. The rate you enter is the rate per period and N is the number of periods. For monthly deposits, divide the annual rate by 12 and multiply the years by 12.
For $100 a month at 5% a year for 20 years, the monthly rate is 5 ÷ 12 = 0.4166667% and there are 240 periods:
FV = $100 × (((1 + 0.05 ÷ 12)240 − 1) ÷ (0.05 ÷ 12)) = $41,103.37
You deposit $24,000 and interest adds $17,103.37. With a present value of 0.01 and End selected, the calculator shows $41,103.40. For a monthly plan where you pick the compounding from a menu and add contributions on top of a starting balance, the investment calculator does the conversion for you.
Future value problems, worked#
Here are common textbook problems, each solved with the formulas above.
| Problem | Working | Future Value |
|---|---|---|
| $3,200 at 7% a year for 3 years | $3,200 × 1.073 | $3,920.14 |
| $250 at 4% a year for 5 years | $250 × 1.045 | $304.16 |
| $100 at 5% a year for 3 years | $100 × 1.053 | $115.76 |
| $100 at 7% a year for 10 years | $100 × 1.0710 | $196.72 |
| $900 at 7% a year for 5 years | $900 × 1.075 | $1,262.30 |
| $625 at 5% a year for 10 years | $625 × 1.0510 | $1,018.06 |
| $1,000 at 6% a year for 8 years | $1,000 × 1.068 | $1,593.85 |
| $2,000 at 3% a year for 2 years | $2,000 × 1.032 | $2,121.80 |
| $800 a year at 6% for 15 years (end of year) | $800 × (1.0615 − 1) ÷ 0.06 | $18,620.78 |
| $2,000 a year at 6% for 8 years (end of year) | $2,000 × (1.068 − 1) ÷ 0.06 | $19,794.94 |
| $100 a month at 5% a year for 20 years | $100 × ((1 + 0.05 ÷ 12)240 − 1) ÷ (0.05 ÷ 12) | $41,103.37 |
Where future value is used#
- Savings goals: what a deposit or a monthly transfer will be worth by a set date.
- Retirement saving: a contribution every pay period is an annuity, and the 401(k) calculator adds an employer match and salary raises to it.
- Comparing offers: the same deposit at two rates or over two terms.
- Finance courses and exams: time value of money questions use these exact formulas.
Sources#
- OpenStax, Principles of Finance, 7.2 Time Value of Money (TVM) Basics (future value of a single amount)
- OpenStax, Principles of Finance, 8.2 Annuities (future value of an ordinary annuity and an annuity due)
- Investor.gov (U.S. Securities and Exchange Commission), What is compound interest?
Frequently asked questions#
What is the future value of $1,000 invested for 8 years at 6%?#
It's $1,593.85. $1,000 × 1.068 = $1,000 × 1.593848 = $1,593.85, and $593.85 of that is interest.
What is the future value of $2,000 a year for 8 years at 6%?#
It's $19,794.94 with each deposit at the end of the year. You put in $16,000 and earn $3,794.94 of interest. With deposits at the start of each year it's $19,794.94 × 1.06 = $20,982.63.
What is the difference between future value and present value?#
Future value is what money today will be worth later. Present value is what a later amount is worth today. They are the same formula turned around: PV = FV ÷ (1 + r)n, so $3,920.14 due in 3 years at 7% has a present value of $3,200.
Does future value include inflation?#
No. The formula gives the amount in future dollars. To see what it would buy at today's prices, divide by 1 plus the inflation rate for each year. At 3% a year, $3,920.14 three years from now buys what $3,587.48 buys today.
Why is an annuity due worth more than an ordinary annuity?#
Each deposit goes in one period earlier, so each earns one more period of interest. The total is the ordinary annuity times (1 + r): $18,620.78 × 1.06 = $19,738.02.
What is the future value of $250 at 4% for 5 years?#
It's $304.16 with interest compounded once a year: $250 × 1.045 = $250 × 1.216653 = $304.16. Interest makes up $54.16 of that.
Related calculators
View all calculators Payment CalculatorPayment calculator: find the monthly payment on a fixed-rate loan, or how long a set monthly payment takes to pay it off, with worked formula examples.
 Personal Loan CalculatorPersonal loan calculator: find the monthly payment, total interest and payoff date for any amount, rate and term, and learn how fees change the real cost.
 Refinance CalculatorRefinance calculator: compare your current loan with a new one to see the monthly savings, the break-even point on closing costs and the total interest.
 Retirement CalculatorRetirement calculator: estimate the savings you need, how much to save, the monthly income your savings can pay and how long the money could last.
 Salary CalculatorSalary calculator: convert pay between hourly, daily, weekly, biweekly, semi-monthly, monthly and yearly, with or without holidays and vacation days.
 Simple Interest CalculatorSimple interest calculator: solve I = Prt for the total, principal, rate or time, with time in days, weeks, months or years, plus worked problems.