Interest Calculator
Interest calculator: see how money grows with monthly compounding, regular additions, tax and inflation, plus simple vs compound interest examples.
Written by
Annie Button
Updated
There was an error with your calculation.
Interest
End Balance: $135,479.01
After Inflation Adjustment: $100,809.11
Total Principal: $99,000.00
Total Interest: $39,224.74
Total Interest after Tax: $36,479.01
Initial investment
Interest after tax
Contributions
Tax
0 yr
5 yr
10 yr
| № | DEPOSIT | INTEREST | ENDING BALANCE |
|---|---|---|---|
| 1 | $32,400.00 | $1,486.44 | $33,886.44 |
| 2 | $7,400.00 | $1,908.58 | $43,195.01 |
| 3 | $7,400.00 | $2,350.77 | $52,945.78 |
| 4 | $7,400.00 | $2,813.97 | $63,159.75 |
| 5 | $7,400.00 | $3,299.17 | $73,858.93 |
| 6 | $7,400.00 | $3,807.43 | $85,066.35 |
| 7 | $7,400.00 | $4,339.82 | $96,806.18 |
| 8 | $7,400.00 | $4,897.51 | $109,103.69 |
| 9 | $7,400.00 | $5,481.69 | $121,985.38 |
| 10 | $7,400.00 | $6,093.62 | $135,479.01 |
| № | DEPOSIT | INTEREST | ENDING BALANCE | |
|---|---|---|---|---|
| 1 | $30,200.00 | $117.03 | $30,317.03 | |
| 2 | $200.00 | $118.25 | $30,635.28 | |
| 3 | $200.00 | $119.49 | $30,954.77 | |
| 4 | $200.00 | $120.72 | $31,275.49 | |
| 5 | $200.00 | $121.97 | $31,597.46 | |
| 6 | $200.00 | $123.22 | $31,920.67 | |
| 7 | $200.00 | $124.47 | $32,245.14 | |
| 8 | $200.00 | $125.72 | $32,570.87 | |
| 9 | $200.00 | $126.99 | $32,897.85 | |
| 10 | $200.00 | $128.25 | $33,226.11 | |
| 11 | $200.00 | $129.53 | $33,555.63 | |
| 12 | $200.00 | $130.80 | $33,886.44 | |
| Year #1 End | ||||
| 13 | $5,200.00 | $151.46 | $39,237.90 | |
| 14 | $200.00 | $152.82 | $39,590.72 | |
| 15 | $200.00 | $154.19 | $39,944.91 | |
| 16 | $200.00 | $155.56 | $40,300.47 | |
| 17 | $200.00 | $156.94 | $40,657.41 | |
| 18 | $200.00 | $158.32 | $41,015.73 | |
| 19 | $200.00 | $159.71 | $41,375.44 | |
| 20 | $200.00 | $161.10 | $41,736.55 | |
| 21 | $200.00 | $162.50 | $42,099.05 | |
| 22 | $200.00 | $163.91 | $42,462.96 | |
| 23 | $200.00 | $165.32 | $42,828.28 | |
| 24 | $200.00 | $166.73 | $43,195.01 | |
| Year #2 End | ||||
| 25 | $5,200.00 | $187.53 | $48,582.54 | |
| 26 | $200.00 | $189.03 | $48,971.57 | |
| 27 | $200.00 | $190.54 | $49,362.11 | |
| 28 | $200.00 | $192.05 | $49,754.17 | |
| 29 | $200.00 | $193.57 | $50,147.74 | |
| 30 | $200.00 | $195.10 | $50,542.84 | |
| 31 | $200.00 | $196.63 | $50,939.47 | |
| 32 | $200.00 | $198.17 | $51,337.63 | |
| 33 | $200.00 | $199.71 | $51,737.34 | |
| 34 | $200.00 | $201.26 | $52,138.60 | |
| 35 | $200.00 | $202.81 | $52,541.41 | |
| 36 | $200.00 | $204.37 | $52,945.78 | |
| Year #3 End | ||||
| 37 | $5,200.00 | $225.31 | $58,371.10 | |
| 38 | $200.00 | $226.96 | $58,798.06 | |
| 39 | $200.00 | $228.62 | $59,226.68 | |
| 40 | $200.00 | $230.28 | $59,656.96 | |
| 41 | $200.00 | $231.95 | $60,088.90 | |
| 42 | $200.00 | $233.62 | $60,522.52 | |
| 43 | $200.00 | $235.30 | $60,957.82 | |
| 44 | $200.00 | $236.99 | $61,394.81 | |
| 45 | $200.00 | $238.68 | $61,833.49 | |
| 46 | $200.00 | $240.38 | $62,273.87 | |
| 47 | $200.00 | $242.09 | $62,715.95 | |
| 48 | $200.00 | $243.80 | $63,159.75 | |
| Year #4 End | ||||
| 49 | $5,200.00 | $264.89 | $68,624.65 | |
| 50 | $200.00 | $266.70 | $69,091.34 | |
| 51 | $200.00 | $268.50 | $69,559.85 | |
| 52 | $200.00 | $270.32 | $70,030.17 | |
| 53 | $200.00 | $272.14 | $70,502.31 | |
| 54 | $200.00 | $273.97 | $70,976.28 | |
| 55 | $200.00 | $275.81 | $71,452.09 | |
| 56 | $200.00 | $277.65 | $71,929.74 | |
| 57 | $200.00 | $279.50 | $72,409.24 | |
| 58 | $200.00 | $281.36 | $72,890.60 | |
| 59 | $200.00 | $283.23 | $73,373.83 | |
| 60 | $200.00 | $285.10 | $73,858.93 | |
| Year #5 End | ||||
| 61 | $5,200.00 | $306.35 | $79,365.28 | |
| 62 | $200.00 | $308.32 | $79,873.60 | |
| 63 | $200.00 | $310.29 | $80,383.88 | |
| 64 | $200.00 | $312.26 | $80,896.14 | |
| 65 | $200.00 | $314.25 | $81,410.39 | |
| 66 | $200.00 | $316.24 | $81,926.63 | |
| 67 | $200.00 | $318.24 | $82,444.87 | |
| 68 | $200.00 | $320.25 | $82,965.12 | |
| 69 | $200.00 | $322.26 | $83,487.39 | |
| 70 | $200.00 | $324.29 | $84,011.67 | |
| 71 | $200.00 | $326.32 | $84,537.99 | |
| 72 | $200.00 | $328.36 | $85,066.35 | |
| Year #6 End | ||||
| 73 | $5,200.00 | $349.78 | $90,616.14 | |
| 74 | $200.00 | $351.91 | $91,168.05 | |
| 75 | $200.00 | $354.05 | $91,722.10 | |
| 76 | $200.00 | $356.20 | $92,278.30 | |
| 77 | $200.00 | $358.35 | $92,836.65 | |
| 78 | $200.00 | $360.52 | $93,397.17 | |
| 79 | $200.00 | $362.69 | $93,959.86 | |
| 80 | $200.00 | $364.87 | $94,524.73 | |
| 81 | $200.00 | $367.06 | $95,091.79 | |
| 82 | $200.00 | $369.26 | $95,661.04 | |
| 83 | $200.00 | $371.46 | $96,232.50 | |
| 84 | $200.00 | $373.68 | $96,806.18 | |
| Year #7 End | ||||
| 85 | $5,200.00 | $395.27 | $102,401.45 | |
| 86 | $200.00 | $397.58 | $102,999.03 | |
| 87 | $200.00 | $399.90 | $103,598.93 | |
| 88 | $200.00 | $402.22 | $104,201.15 | |
| 89 | $200.00 | $404.55 | $104,805.71 | |
| 90 | $200.00 | $406.90 | $105,412.60 | |
| 91 | $200.00 | $409.25 | $106,021.85 | |
| 92 | $200.00 | $411.61 | $106,633.46 | |
| 93 | $200.00 | $413.98 | $107,247.44 | |
| 94 | $200.00 | $416.36 | $107,863.80 | |
| 95 | $200.00 | $418.75 | $108,482.55 | |
| 96 | $200.00 | $421.14 | $109,103.69 | |
| Year #8 End | ||||
| 97 | $5,200.00 | $442.93 | $114,746.62 | |
| 98 | $200.00 | $445.42 | $115,392.04 | |
| 99 | $200.00 | $447.92 | $116,039.96 | |
| 100 | $200.00 | $450.43 | $116,690.39 | |
| 101 | $200.00 | $452.95 | $117,343.34 | |
| 102 | $200.00 | $455.48 | $117,998.82 | |
| 103 | $200.00 | $458.02 | $118,656.84 | |
| 104 | $200.00 | $460.57 | $119,317.41 | |
| 105 | $200.00 | $463.13 | $119,980.54 | |
| 106 | $200.00 | $465.70 | $120,646.24 | |
| 107 | $200.00 | $468.28 | $121,314.52 | |
| 108 | $200.00 | $470.87 | $121,985.38 | |
| Year #9 End | ||||
| 109 | $5,200.00 | $492.84 | $127,678.23 | |
| 110 | $200.00 | $495.53 | $128,373.76 | |
| 111 | $200.00 | $498.22 | $129,071.98 | |
| 112 | $200.00 | $500.93 | $129,772.91 | |
| 113 | $200.00 | $503.65 | $130,476.55 | |
| 114 | $200.00 | $506.37 | $131,182.92 | |
| 115 | $200.00 | $509.11 | $131,892.03 | |
| 116 | $200.00 | $511.86 | $132,603.89 | |
| 117 | $200.00 | $514.62 | $133,318.50 | |
| 118 | $200.00 | $517.38 | $134,035.89 | |
| 119 | $200.00 | $520.16 | $134,756.05 | |
| 120 | $200.00 | $522.95 | $135,479.01 | |
| Year #10 End | ||||
Interest calculator at a glance#
How much is $5,500 after 28 years at 5.25% interest?#
Compounded once a year, $5,500 at 5.25% grows to $23,045.26 after 28 years, which is $5,500 × 1.052528. That's the usual textbook answer when the problem doesn't name a compounding period. Compounded monthly, as this calculator does it, the balance is $23,844.22. With simple interest it would be $13,585.00.
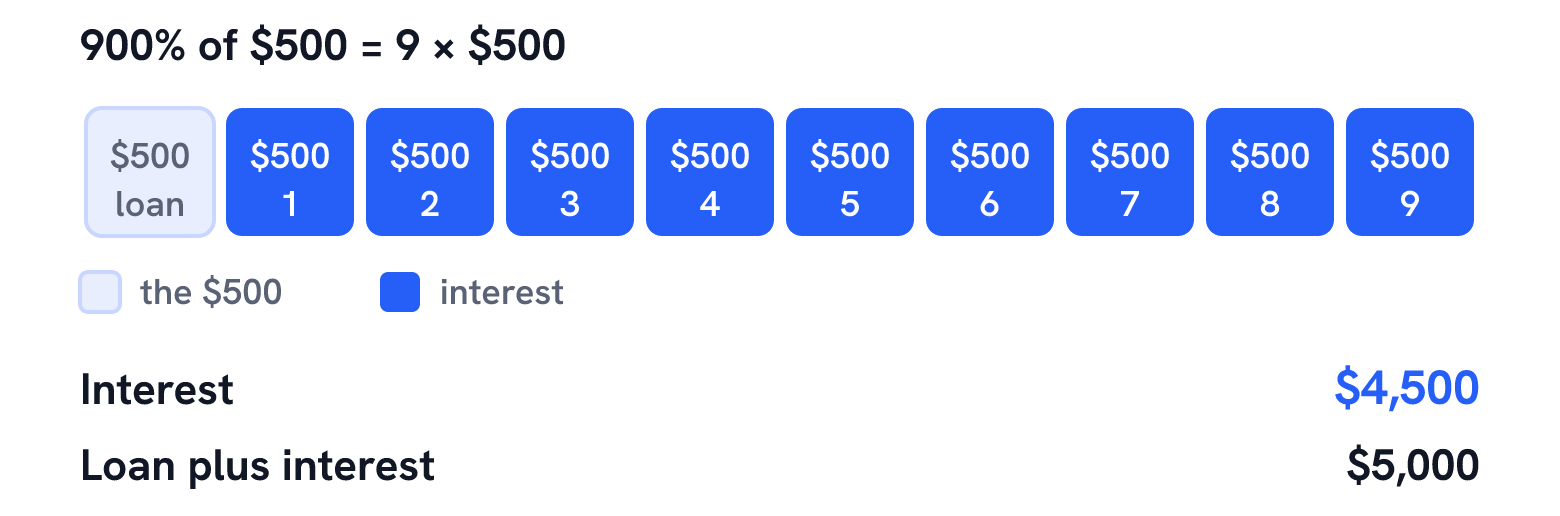
What is 900 percent interest on $500?#
900% interest on $500 is $4,500, because 900% means 9 times the amount and 9 × $500 = $4,500. With the original $500, the total is $5,000. That assumes the 900% is charged once, as simple interest.
How do you calculate interest?#
Simple interest is principal × rate × time, or I = Prt. Compound interest adds each period's interest to the balance, so the next period earns interest on it too: A = P(1 + r/n)nt. In both, write the rate as a decimal and the time in years.
Simple and compound interest, side by side#
Interest is what a lender charges for using money, or what a bank or investment pays you for keeping it there. It's set as a percentage of the principal, the amount borrowed or saved. Two methods cover most problems.
With simple interest, the interest is figured on the original principal only, so it's the same every year. OpenStax Contemporary Mathematics gives it as I = P × r × t, with P the principal, r the annual rate as a decimal and t the time in years.
With compound interest, each period's interest is added to the balance, and the next period's interest is figured on the new, larger balance. The SEC shows how that adds up: $100 earning 5% a year grows to over $162 in 10 years and almost $340 in 25, without another deposit. OpenStax writes the compound interest formula as A = P(1 + r/n)nt, where n is the number of times interest is added per year.
Take the $5,500 at 5.25% for 28 years from the homework question:
- Simple interest: $5,500 × 0.0525 × 28 = $8,085.00 of interest, for $13,585.00.
- Compounded yearly: $5,500 × 1.052528 = $23,045.26, or $17,545.26 of interest.
- Compounded monthly: $5,500 × (1 + 0.0525 ÷ 12)336 = $23,844.22, or $18,344.22 of interest.
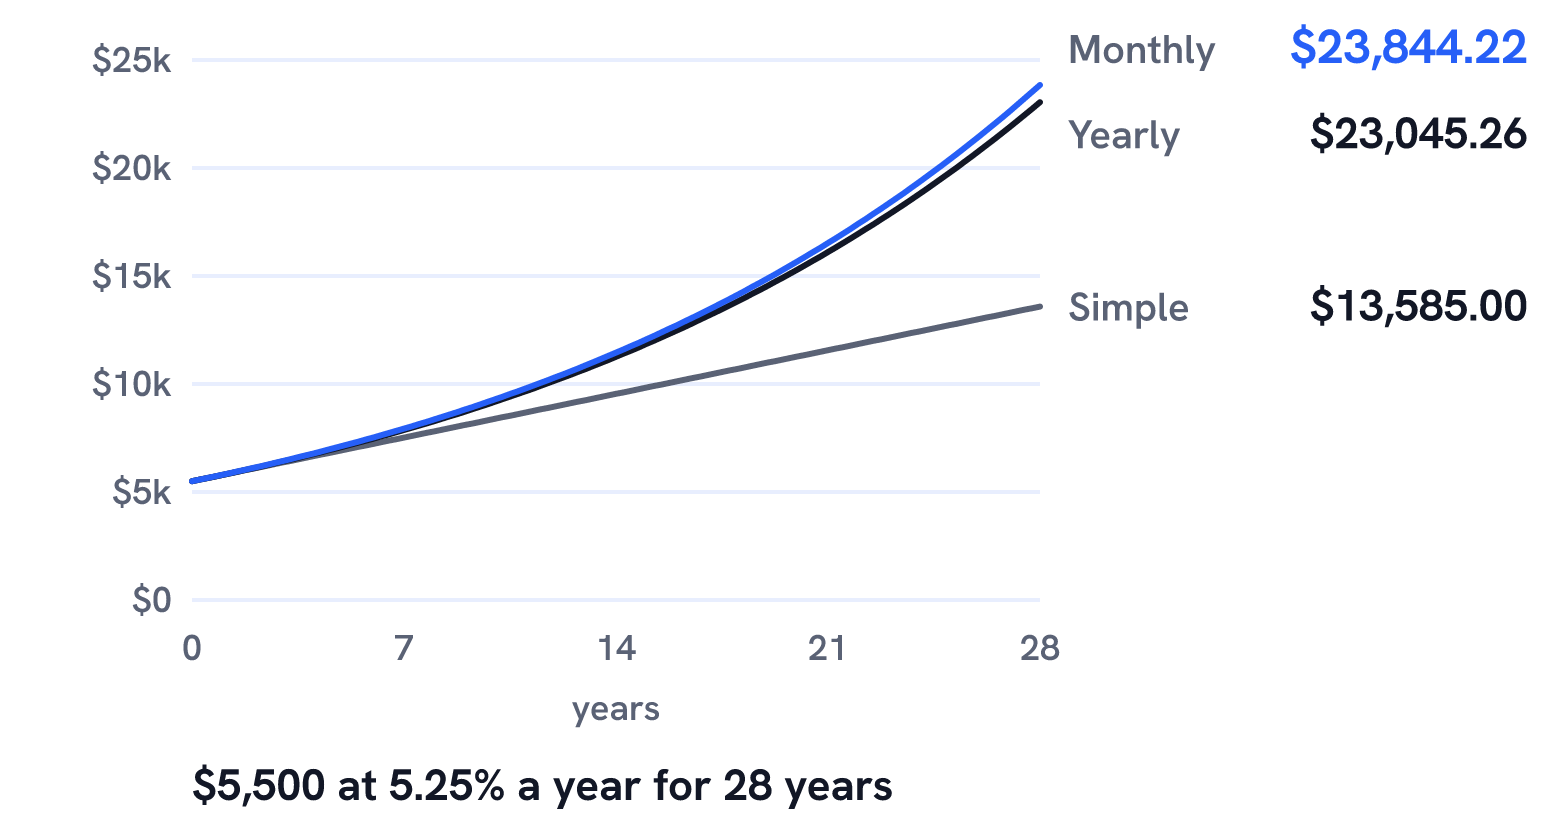
For the first year the three are close. Over 28 years, compounding more than doubles the interest, because the interest keeps earning interest.
Working the $5,500 problem to the cent#
The question reads: $5,500 is placed in an account with an annual interest rate of 5.25%, how much will be in the account after 28 years, to the nearest cent? When a problem gives an annual rate and no compounding period, the expected method is usually yearly compounding, so n = 1.
- Write the rate as a decimal: 5.25% = 0.0525.
- Add 1 to get the yearly growth factor: 1.0525.
- Raise it to the number of years: 1.052528 = 4.190047.
- Multiply by the principal: $5,500 × 4.190047 = $23,045.26.
Keep all the digits until the last step and round only the final answer. If your course compounds monthly or quarterly, use those periods instead, and the compound interest calculator lets you pick the compounding period. Check which method your textbook expects, because the answers differ by hundreds of dollars here.
What the calculator above does#
This calculator compounds monthly. It splits the annual rate into 12 and adds interest to the balance every month. Enter:
- Starting principal: the amount you start with.
- Annual addition and monthly addition: money you add along the way, at the beginning or the end of each period.
- Interest rate: the annual rate.
- Investment length in years.
- Tax rate: the share of each month's interest you lose to tax, if any. The interest that's left is what compounds.
- Inflation rate: used to show what the end balance is worth at today's prices.
It shows the end balance, the balance after the inflation adjustment, the total principal you put in, the total interest before and after tax, a chart and annual and monthly schedules. For the homework problem, enter $5,500, 5.25% and 28 years with the additions, tax and inflation set to 0, and the end balance is $23,844.22, the monthly-compounding answer.
Additions make a big difference. With $100 added at the end of every month, the same $5,500 at 5.25% grows to $100,079.94 after 28 years. You put in $39,100.00 of that and the rest, $60,979.94, is interest.
This gives an estimate, not financial advice.
What 900 percent interest means#
A percent is a number out of 100, so 900% is 900 out of 100, or 9 times the amount. 900% interest on $500 is 9 × $500 = $4,500, and the loan plus interest is $5,000. That's the simple, one-time reading of the question. The percentage calculator's simple percentage mode gives the same 4,500 for 900% of 500.
Don't enter 900% in the calculator above for this question. It compounds monthly, so 900% a year becomes 75% a month on a growing balance, and $500 turns into $412,502.50 in one year. That's the real effect of compounding at an extreme rate, and it's why the compounding period matters so much at high rates.
Finding the rate, the time or the principal#
Many interest problems give you the interest and ask for something else. This calculator only works forward from the principal, so for those, rearrange I = Prt or use a calculator with solve-for modes. A few from real homework searches:
- Time: a $6,500 business loan builds up $3,185 of simple interest at 7% a year. t = 3,185 ÷ (6,500 × 0.07) = 7 years.
- Rate: $2,000 earns $240 of simple interest in 3 years. r = 240 ÷ (2,000 × 3) = 0.04, or 4% a year.
- Interest: $100 borrowed for one year at 5% costs $100 × 0.05 × 1 = $5.00.
- Balance: $1,900 at 2% simple interest for 3 years grows to $1,900 × (1 + 0.02 × 3) = $2,014.00.
The simple interest calculator solves for the total, the principal, the rate or the time. The compound interest calculator does the same for compound interest, with compounding from yearly to continuous.
Simple and compound balances by year#
The table follows $5,500 at 5.25% through the years with the three methods. The last column is what the calculator above shows as the end balance for each length.
| Years | Simple Interest | Compounded Yearly | Compounded Monthly (this calculator) |
|---|---|---|---|
| 1 | $5,788.75 | $5,788.75 | $5,795.80 |
| 5 | $6,943.75 | $7,103.51 | $7,146.88 |
| 10 | $8,387.50 | $9,174.53 | $9,286.88 |
| 15 | $9,831.25 | $11,849.34 | $12,067.68 |
| 20 | $11,275.00 | $15,303.99 | $15,681.13 |
| 25 | $12,718.75 | $19,765.84 | $20,376.56 |
| 28 | $13,585.00 | $23,045.26 | $23,844.22 |
Sources#
- OpenStax, Contemporary Mathematics, section 6.3: Simple Interest
- OpenStax, Contemporary Mathematics, section 6.4: Compound Interest
- U.S. Securities and Exchange Commission, Project C.H.A.N.G.E.: Creating Choices
Frequently asked questions#
Is the $5,500 answer $23,045.26 or $23,844.22?#
Both are right for different compounding. $23,045.26 assumes interest is added once a year, the usual reading of an annual rate. $23,844.22 assumes monthly compounding, which is what this calculator uses.
How do I calculate interest on a loan?#
For simple interest, multiply the principal by the annual rate and the years: $500 at 15% for 2 years is $150. An amortized loan, such as a fixed-rate mortgage, charges interest on the remaining balance each month instead, and the amortization calculator shows how that splits each payment.
What is an annual interest rate?#
It's the percentage of the principal charged or paid over one year. If interest is added more often, the rate is split across the periods: 5.25% compounded monthly is 5.25% ÷ 12 = 0.4375% a month.
What does the tax rate field do?#
It takes that percentage off each month's interest before the interest is added to the balance. With a tax rate of 0, all the interest stays in the account and compounds.
How does the inflation adjustment work?#
It divides the end balance by (1 + inflation rate) once for every year, which shows roughly what the balance is worth at today's prices. At 3% inflation over 28 years, the $23,844.22 is worth $10,421.75 at today's prices.
Does it matter if I add money at the beginning or the end of the month?#
A little. Money added at the beginning earns interest for that month too. With $100 a month, $5,500 at 5.25% for 28 years ends at $100,413.47 with additions at the beginning, against $100,079.94 at the end.
Related calculators
View all calculators Personal Loan CalculatorPersonal loan calculator: find the monthly payment, total interest and payoff date for any amount, rate and term, and learn how fees change the real cost.
 Refinance CalculatorRefinance calculator: compare your current loan with a new one to see the monthly savings, the break-even point on closing costs and the total interest.
 Retirement CalculatorRetirement calculator: estimate the savings you need, how much to save, the monthly income your savings can pay and how long the money could last.
 Salary CalculatorSalary calculator: convert pay between hourly, daily, weekly, biweekly, semi-monthly, monthly and yearly, with or without holidays and vacation days.
 Simple Interest CalculatorSimple interest calculator: solve I = Prt for the total, principal, rate or time, with time in days, weeks, months or years, plus worked problems.
 Simple Investment CalculatorSimple investment calculator: find what a lump sum grows to at a set rate and compounding schedule, or the amount, rate or contribution a target needs.