
Simple Interest Calculator
Simple interest calculator: solve I = Prt for the total, principal, rate or time, with time in days, weeks, months or years, plus worked problems.
Written by
Nella Cheng
Updated
There was an error with your calculation.
Simple interest calculator at a glance#
What is the simple interest formula?#
The simple interest formula is I = P × r × t: the principal times the annual rate as a decimal times the time in years. The total at the end is A = P + I, which is the same as P(1 + rt). $18,500 at 4.8% for 4 years earns 18,500 × 0.048 × 4 = $3,552, for a total of $22,052.
What simple interest rate makes $5,000 grow to $5,250 in 4 years?#
The rate is 1.25% a year. The interest is $5,250 − $5,000 = $250, and r = I ÷ (P × t) = 250 ÷ (5,000 × 4) = 0.0125. In the calculator, choose Solve for R and enter a total of $5,250, a principal of $5,000 and 4 years.
How much is $4,370 at 2.35% simple interest after 5 months?#
The balance is $4,412.79. Five months is 5 ÷ 12 of a year, so the interest is 4,370 × 0.0235 × 5 ÷ 12 = $42.79. In the calculator, enter 5 and choose months as the time unit.
How simple interest works#
Simple interest is figured on the original principal only. The interest never earns interest, so the same amount is added every year. That's the difference from compound interest, where each period's interest joins the balance and earns interest too.
Take a college loan of $18,500 at 4.8% simple interest for 4 years, with nothing repaid until the end. One year of interest is 18,500 × 0.048 = $888. Four years is 4 × $888 = $3,552. The total cost at the end of 4 years is $18,500 + $3,552 = $22,052.
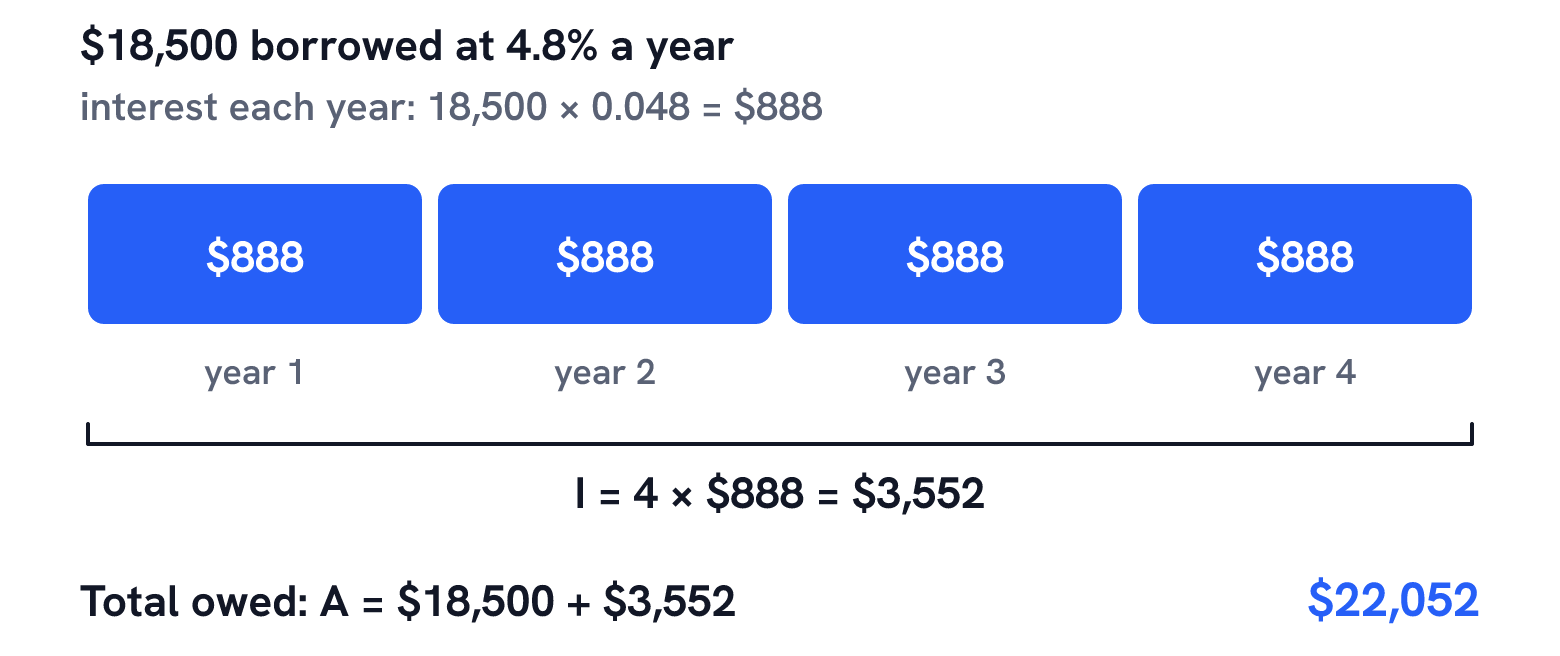
OpenStax Contemporary Mathematics states the formula as I = P × r × t, where P is the principal, r is the annual interest rate in decimal form and t is the time in years. The total repaid is P + I. Write the rate as a decimal first: 4.8% is 0.048, 2.35% is 0.0235 and 5 3/4% is 0.0575. To turn a decimal answer such as 0.0125 back into a percent, multiply by 100 or use the decimal to percent calculator.
Solving for interest, principal, rate or time#
I = Prt has four letters, so if you know any three you can find the fourth. The calculator has four modes, Solve for A, P, R and T. It works with the total A, the principal plus the interest, rather than the interest alone. When a problem gives you the interest, add it to the principal to get A, or rearrange the formula by hand as below.
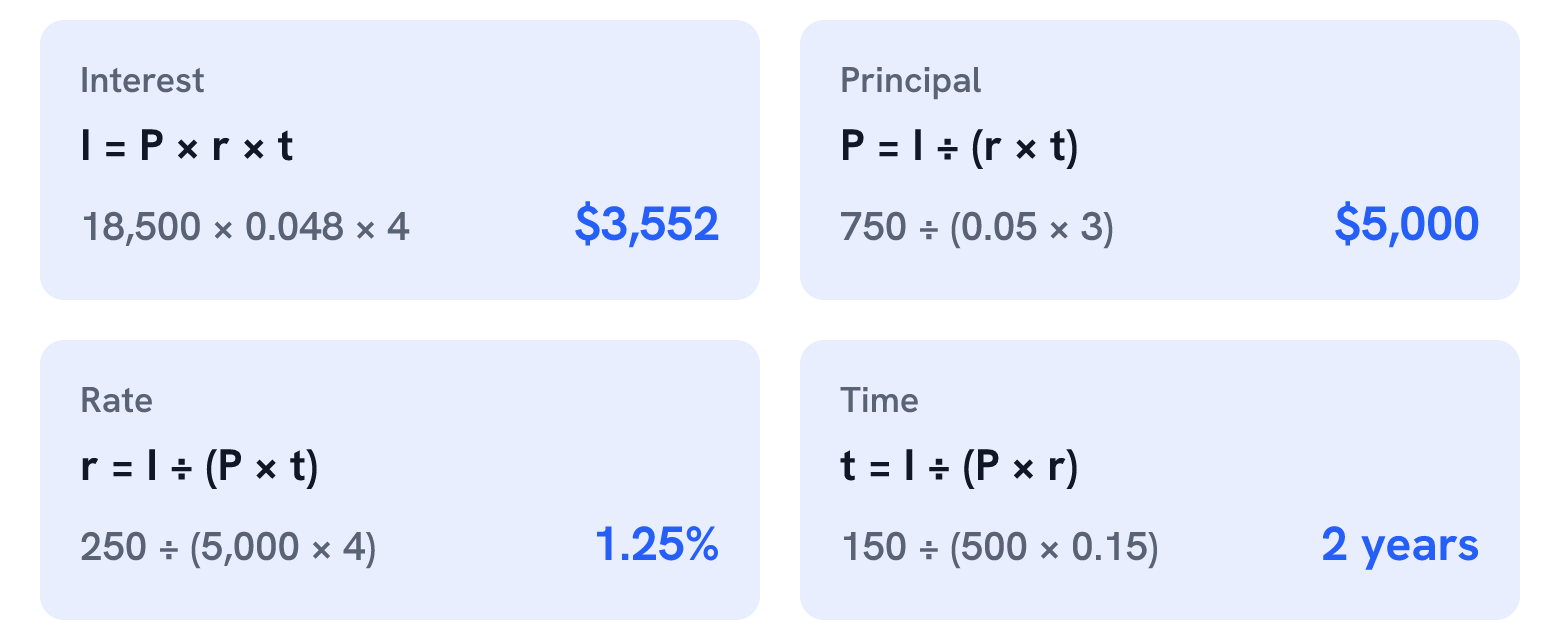
- Interest and total: I = P × r × t, then A = P + I. The $18,500 loan gives I = $3,552 and A = $22,052. The calculator's Solve for A mode shows A = $22,052.00.
- Principal: P = I ÷ (r × t). Find the principal when I = 750, r = 5% and t = 3 years: P = 750 ÷ (0.05 × 3) = 750 ÷ 0.15 = $5,000. If someone earned $360 in 4 years at 3%, they invested 360 ÷ (0.03 × 4) = $3,000.
- Rate: r = I ÷ (P × t). For $5,000 to grow to $5,250 in 4 years, r = 250 ÷ (5,000 × 4) = 0.0125, or 1.25% a year.
- Time: t = I ÷ (P × r). To find the time when I = $150, P = $500 and r = 15%, t = 150 ÷ (500 × 0.15) = 150 ÷ 75 = 2 years. The calculator's Solve for T mode, with a total of $650, gives T = 2 years.
The calculator's Solve for P mode starts from the total, not the interest. It answers questions like how much to deposit now to have $5,750 in 3 years at 5%: P = 5,750 ÷ (1 + 0.05 × 3) = $5,000. OpenStax calls this the present value.
This gives an estimate, not financial advice.
Months, weeks and days: converting time to years#
The rate in simple interest problems is almost always a yearly rate, so the time has to be in years too. OpenStax writes a part of a year as a fraction: divide months by 12 and days by 365.
- Months: Julie deposits $4,370 at 2.35% for 5 months. t = 5 ÷ 12, so I = 4,370 × 0.0235 × 5 ÷ 12 = $42.79 and the balance is $4,412.79.
- Months: Casey borrows $3,200 at 4.25% for 4 months. I = 3,200 × 0.0425 × 4 ÷ 12 = $45.33.
- Answer in months: how long until $2,000 earns $250 at 3%? t = 250 ÷ (2,000 × 0.03) = 4.1667 years. Multiply by 12 to get 50 months.
The calculator's time box takes days (365 a year), days (360 a year), weeks, months, quarters or years, and converts for you. The 360-day option follows a banking habit that OpenStax mentions: some banks count 360 days in a year, which makes the interest slightly larger. The same $4,370 at 2.35% for 152 days gives $4,412.77 on a 365-day year and $4,413.36 on a 360-day year. Solve for T always gives the answer in years, so multiply by 12 for months.
Simple interest compared with compound interest#
On short terms the two are close. Over longer terms compound interest pulls ahead, because the interest keeps earning interest. If the $18,500 loan grew at 4.8% compounded once a year instead, it would reach $22,316.03 after 4 years rather than $22,052. The compound interest calculator works out the compound version, and the interest calculator compounds monthly with regular additions, and its page compares simple and compound interest side by side.
The OpenStax chapter's own examples include a certificate of deposit that pays simple interest and a 45-day simple interest loan.
More worked problems#
These come from real homework questions. Each answer uses I = Prt, A = P + I or one of the rearranged forms, rounded to the cent.
| Problem | Working | Answer |
|---|---|---|
| Maya saves $850 at 5% for 3 years. Balance? | A = 850 × (1 + 0.05 × 3) | $977.50 |
| Interest on $48,000 at 3.2% for 5 years? | I = 48,000 × 0.032 × 5 | $7,680.00 |
| Casey borrows $3,200 at 4.25% for 4 months. Interest? | I = 3,200 × 0.0425 × 4 ÷ 12 | $45.33 |
| $3,800 at 7.3% for 6 months. Interest? | I = 3,800 × 0.073 × 6 ÷ 12 | $138.70 |
| Interest when P = $19,574, r = 7.5%, t = 3.25 years? | I = 19,574 × 0.075 × 3.25 | $4,771.16 |
| Brandy repays $12,500 at 3% over 4 years. Total? | A = 12,500 × (1 + 0.03 × 4) | $14,000.00 |
| Christopher deposits $1,500 at 4.3% for 15 years. Total? | A = 1,500 × (1 + 0.043 × 15) | $2,467.50 |
| Mauricio borrows $65,000 at 5 3/4% for 10 years. Interest? | I = 65,000 × 0.0575 × 10 | $37,375.00 |
| Dylan pays $1,272 interest on $6,000 over 4 years. Rate? | r = 1,272 ÷ (6,000 × 4) | 5.3% |
| Ethan's $5,000 at 8% earns $1,600. How many years? | t = 1,600 ÷ (5,000 × 0.08) | 4 years |
| How many months for $2,500 to earn $150 at 2%? | t = 150 ÷ (2,500 × 0.02) × 12 | 36 months |
Sources#
Frequently asked questions#
How do you calculate simple interest?#
Multiply the principal by the annual rate as a decimal and by the time in years. $850 at 5% for 3 years is 850 × 0.05 × 3 = $127.50, so the balance is $977.50.
How do you find the principal from the interest?#
Divide the interest by the rate times the time: P = I ÷ (r × t). With I = $750, r = 5% and t = 3 years, P = 750 ÷ 0.15 = $5,000.
How do you find the rate in simple interest?#
Divide the interest by the principal times the time: r = I ÷ (P × t). Dylan paid $1,272 of interest on $6,000 over 4 years, so r = 1,272 ÷ 24,000 = 0.053, or 5.3%.
How do you find the time in simple interest?#
Divide the interest by the principal times the rate: t = I ÷ (P × r). Ethan's $5,000 at 8% earns $1,600 in 1,600 ÷ 400 = 4 years.
How do you convert months to years for simple interest?#
Divide by 12. Five months is 5 ÷ 12 = 0.4167 years, and 8 months is 8 ÷ 12 = 0.6667 years. To turn a time in years back into months, multiply by 12.
Can the calculator solve for the interest directly?#
It shows the total A, so subtract the principal to get the interest. For $18,500 at 4.8% for 4 years it shows A = $22,052.00, and $22,052.00 − $18,500 = $3,552.00 of interest.
What is the total cost of an $18,500 loan at 4.8% for 4 years?#
The total is $22,052: the $18,500 borrowed plus $3,552 of simple interest. That assumes nothing is repaid until the end of the 4 years.
Related calculators
View all calculators APR CalculatorAPR calculator: find the real APR of a loan or mortgage once fees and points are counted, with the payment, total interest and an amortization schedule.
 Auto Loan CalculatorAuto loan calculator: estimate your monthly car payment, total interest and total cost from price, down payment, trade-in, sales tax, fees, rate and term.
 Business Loan CalculatorBusiness loan calculator: estimate the payment, total interest and real rate (APR) of a small business loan with fees, paid monthly, weekly or quarterly.
 Compound Interest CalculatorCompound interest calculator: find the balance, principal, rate or time for any compounding period from yearly to continuous, with worked examples.
 Future Value CalculatorFuture value calculator: find what a starting amount plus regular deposits will be worth after any number of periods, with deposits at the start or end.
 Interest CalculatorInterest calculator: see how money grows with monthly compounding, regular additions, tax and inflation, plus simple vs compound interest examples.