
Retirement Calculator
Retirement calculator: estimate the savings you need, how much to save, the monthly income your savings can pay and how long the money could last.
Written by
Nella Cheng
Updated
There was an error with your calculation.
Result
$553,407 at Age 65
Savings Needed at 65: $1,516,653
Equivalent Purchase Power Now: $624,841
Lifestyle after Retirement: $55,198
You will have
You will need
| MONTHLY INCOME AFTER RETIREMENT (IF SAVED $553,407): | ||
|---|---|---|
| ACTUAL AMOUNT | TODAY'S MONEY | |
| Total | $4,600 | $1,895 |
| From Savings | $3,100 | $1,277 |
| From Social Security | $1,200 | $494 |
| From Other Income | $300 | $124 |
| MONTHLY INCOME AFTER RETIREMENT (IF SAVED $1,516,653): | ||
|---|---|---|
| ACTUAL AMOUNT | TODAY'S MONEY | |
| Total | $9,911 | $4,083 |
| From Savings | $8,411 | $3,465 |
| From Social Security | $1,200 | $494 |
| From Other Income | $300 | $124 |
| IF YOU SAVE EVERY MONTH UNTIL 65 | |
|---|---|
| Amount to Save Every Month | $644.11 |
| Total Principal | $261,880.23 |
| Total Interest | $538,119.77 |
| IF YOU SAVE EVERY YEAR UNTIL 65 | |
| Amount to Save Every Year | $7,939.66 |
| Total Principal | $268,189.86 |
| Total Interest | $531,810.14 |
| IF YOU HAVE IT NOW | |
| Additional Amount Needed | $109,288.10 |
| Total Principal | $139,288.10 |
| Total Interest | $660,711.90 |
| Result | |
|---|---|
| Balance at the retirement age of 65 | $646,653.85 |
| Equivalent to current purchase power of | $266,412.83 |
| The amount you can withdraw monthly at 65 and increase 3% annually | $3,573.24 |
| Equivalent to current purchase power of | $1,472.13 |
| The amount you can withdraw monthly from 65 to 85 | $4,573.73 |
| At age 65, equivalent to current purchase power of | $1,884.32 |
| At age 85, equivalent to current purchase power of | $1,043.30 |
Result
| WITHDRAW LENGTH | WITHDRAW AMOUNT |
|---|---|
| 5 years | $11,555.39/month |
| 10 years | $6,613.44/month |
| 15 years | $5,011.76/month |
| 20 years | $4,243.75/month |
| 25 years | $3,807.73/month |
| 30 years | $3,536.22/month |
| 35 years | $3,357.34/month |
Retirement calculator at a glance#
What is 4% of $50,000?#
4% of $50,000 is $2,000, because $50,000 × 0.04 = $2,000. That's about $166.67 a month. Under the 4% rule, $2,000 would be the first-year withdrawal from a $50,000 retirement balance.
What is the 4% rule?#
It's a rule of thumb for retirement withdrawals: take 4% of your savings in the first year, then raise that dollar amount each year with inflation. It comes from a 1994 study by financial planner William Bengen, who tested withdrawal rates against U.S. stock and bond returns from 1926 on. In his data, a portfolio of 50% stocks and 50% intermediate-term Treasury notes never ran out in less than 33 years at a 4% first-year withdrawal.
How much can I withdraw from $1.2 million?#
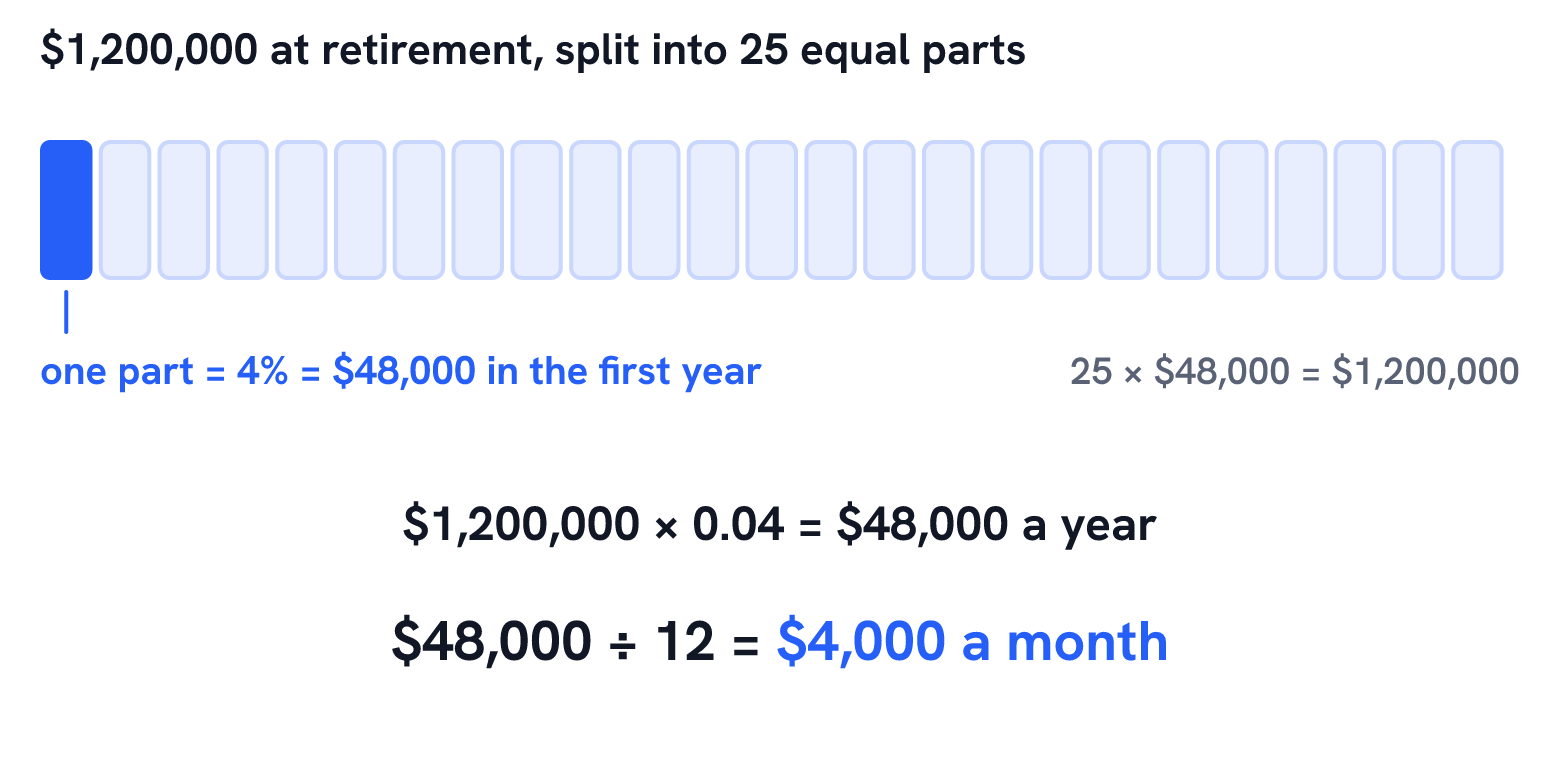
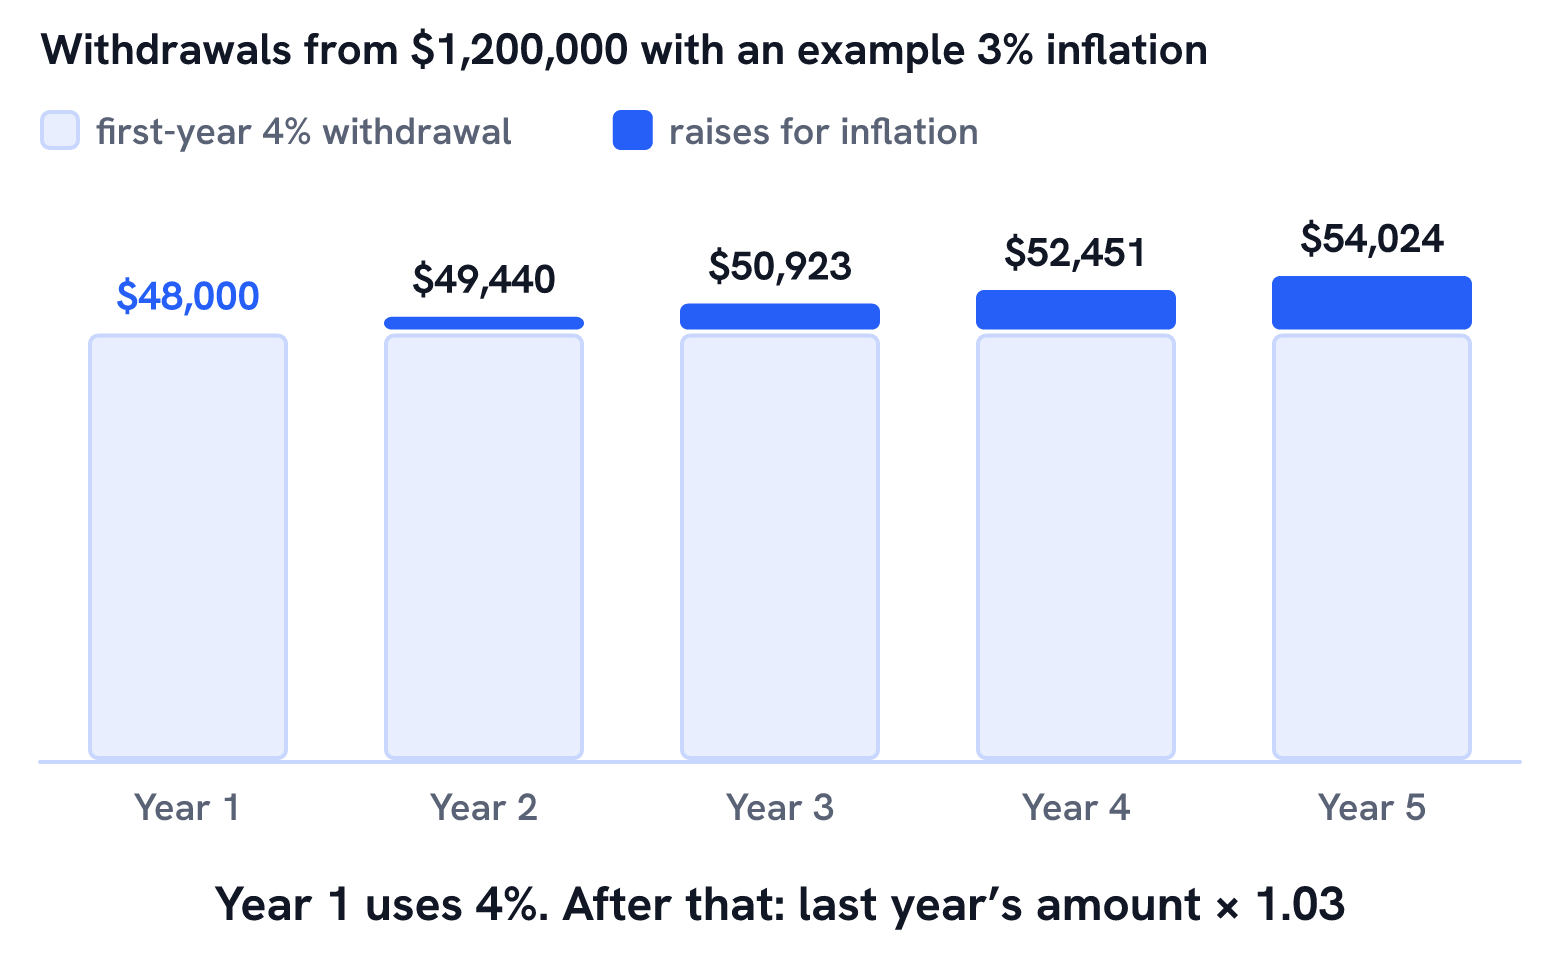
Under the 4% rule, $48,000 in the first year, which is $4,000 a month. In the second year you'd take $48,000 plus inflation, so with an example 3% inflation that's $49,440.
How the 4% rule works#
The rule has two steps, and only the first one uses the 4%.
- In the first year of retirement, withdraw 4% of the balance you start with. For $1,200,000 that's $1,200,000 × 0.04 = $48,000.
- In every later year, take last year's dollar amount and raise it by that year's inflation. The 4% isn't applied to the balance again.
Bengen's paper says it in so many words: after the first year, the withdrawal rate is no longer used, and each year's amount is last year's withdrawal plus an inflation factor. The point is a steady standard of living. With an example 3% inflation, the $1,200,000 retiree takes $48,000, then $49,440, $50,923.20, $52,450.90 and $54,024.42 over the first five years, whatever the markets do.
A quick way to work out 4% of any balance is to divide by 25, since 4% is one twenty-fifth. $1,200,000 ÷ 25 = $48,000. The percentage calculator does the same for any percent.
Where the 4% figure comes from#
Bengen's article, "Determining Withdrawal Rates Using Historical Data", ran in the Journal of Financial Planning in October 1994. He used yearly U.S. returns for common stocks, intermediate-term Treasury notes and inflation going back to 1926. Then he asked a simple question: starting in each year, how long would a portfolio last if the retiree took a first-year percentage and then raised it with inflation?
His main findings, for a portfolio of 50% stocks and 50% intermediate-term Treasury notes:
- 3% lasted at least 50 years in every starting year he tested, which he called absolutely safe to the extent history is a guide.
- 4% never ran out in less than 33 years, and in most cases lasted 50 years or longer.
- 4.25% could run out in as little as 28 years.
- 5% he called risky, and 6% or more "gambling".
He recommended keeping 50% to 75% of the portfolio in stocks, and he assumed the money sat in tax-deferred accounts.
The limits of the 4% rule#
The rule is a summary of what happened in past U.S. markets, not a promise. Returns and inflation in the years ahead can be worse than anything in Bengen's data. In his tests the hardest retirements were those that began in the years before the 1973 to 1974 downturn, when falling stock prices came with high inflation. The 33-year result also fits a retirement of about 30 years. Bengen suggested planning for your life expectancy plus 5 to 10 years, so someone retiring early needs the money to last longer than a 65-year-old does.
Investor.gov notes that all investments involve some degree of risk and that inflation reduces purchasing power. Treat 4% as a starting point for a conversation with your own numbers, and run more than one withdrawal rate.
This gives an estimate, not financial advice.
What this retirement calculator does#
The calculator above doesn't apply the 4% rule itself. It has four modes, picked from the menu at the top:
- How much to retire: projects your savings at retirement from what you have now plus a percent of income saved each year, and estimates the savings needed to replace a percent of your income after expected Social Security and other monthly income, with inflation taken into account.
- How to save for retirement?: the amount to save every month or every year to reach a target by your retirement age, or the extra lump sum you'd need today.
- How much can be withdrawn?: grows your savings and contributions to retirement, then shows a monthly withdrawal that rises with inflation each year and runs out at your life expectancy, alongside a fixed monthly amount.
- How long can your money last?: takes a balance, a fixed monthly withdrawal and a return, and shows how long the money lasts, or that it lasts indefinitely if the return covers the withdrawal.
To test a 4% plan, use How long can your money last? with $1,200,000 and $4,000 a month. Keep in mind it holds the withdrawal flat and the return steady. At a steady example 4% return, the money lasts 102 years and 7.2 months, and at 5% the monthly return of $4,889 covers the $4,000 forever. Those results look safe only because the withdrawal never rises.
To come closer to the 4% rule, enter a return after inflation and read the $4,000 as today's dollars. An example 5% return with 3% inflation is roughly a 2% real return, and at 2% the calculator shows the $1,200,000 lasting 34 years and 6.6 months. At an example 1% real return it's 28 years and 9.1 months.
4% of common retirement balances#
The first-year withdrawal under the 4% rule, a year and a month, for common balances.
| Balance | 4% in the First Year | per Month |
|---|---|---|
| $35,000 | $1,400.00 | $116.67 |
| $50,000 | $2,000.00 | $166.67 |
| $100,000 | $4,000.00 | $333.33 |
| $250,000 | $10,000.00 | $833.33 |
| $500,000 | $20,000.00 | $1,666.67 |
| $750,000 | $30,000.00 | $2,500.00 |
| $1,000,000 | $40,000.00 | $3,333.33 |
| $1,200,000 | $48,000.00 | $4,000.00 |
| $1,500,000 | $60,000.00 | $5,000.00 |
| $2,000,000 | $80,000.00 | $6,666.67 |
Turning it around: savings for a target income#
Divide the yearly income you want from savings by 0.04, which is the same as multiplying it by 25. $40,000 a year needs $1,000,000, $48,000 needs $1,200,000 and $60,000 needs $1,500,000. Count only the income that has to come from savings: Social Security or a pension is on top. To see how long it takes to build that balance, the 401(k) calculator and the investment calculator project contributions and growth.
Sources#
- William P. Bengen, Determining Withdrawal Rates Using Historical Data, Journal of Financial Planning, October 1994 (FPA reprint, March 2004)
- Investor.gov (U.S. Securities and Exchange Commission), What is Risk?
- IRS, 401(k) Resource Guide: Plan Participants, 401(k) Plan Overview
Frequently asked questions#
What is 4% of $35,000?#
$1,400 a year, from $35,000 × 0.04. That's about $116.67 a month.
How much do I need to retire on $40,000 a year?#
Under the 4% rule, $1,000,000 in savings, since $40,000 ÷ 0.04 = $1,000,000. If Social Security or a pension covers part of the $40,000, you need savings only for the rest.
Is the 4% rule still safe?#
Nobody can promise that. For a portfolio of 50% stocks and 50% intermediate-term Treasury notes, it held up in U.S. market history from 1926 into the early 1990s, but the future can be worse. With that mix, Bengen found that 3% lasted at least 50 years in every starting year he tested, so a lower first-year rate gives more margin.
Does the 4% rule include Social Security?#
No. It covers withdrawals from your savings only. Social Security and pensions are extra income on top. The How much to retire mode of this calculator lets you enter both as monthly amounts.
Is the 4% withdrawal before or after tax?#
Before. It's the amount you take out of the account. The IRS says money in a traditional 401(k) isn't subject to federal income tax until it's distributed, so your spending money can be less than the withdrawal.
How long will $1.2 million last at $4,000 a month?#
It depends on returns and on whether the $4,000 rises with inflation. In this calculator, at a steady example 2% return after inflation, $1,200,000 lasts 34 years and 6.6 months with $4,000 a month at today's prices.
Related calculators
View all calculators 401K Calculator401k calculator: project your 401(k) balance at retirement from your salary, contribution, employer match, raises and return, plus the monthly payout.
 Amortization CalculatorAmortization calculator: get the monthly payment, total interest and a full annual and monthly amortization schedule for your fixed-rate loan.
 APR CalculatorAPR calculator: find the real APR of a loan or mortgage once fees and points are counted, with the payment, total interest and an amortization schedule.
 Auto Loan CalculatorAuto loan calculator: estimate your monthly car payment, total interest and total cost from price, down payment, trade-in, sales tax, fees, rate and term.
 Business Loan CalculatorBusiness loan calculator: estimate the payment, total interest and real rate (APR) of a small business loan with fees, paid monthly, weekly or quarterly.
 Compound Interest CalculatorCompound interest calculator: find the balance, principal, rate or time for any compounding period from yearly to continuous, with worked examples.