APR Calculator
APR calculator: find the real APR of a loan or mortgage once fees and points are counted, with the payment, total interest and an amortization schedule.
Written by
Alize Mendez
Updated
There was an error with your calculation.
Result
| Real APR | 5.219% |
|---|---|
| Amount Financed | $100,000.00 |
| Upfront Out-of-Pocket Fees | $1,000.00 |
| Payment Every Month | $1,060.66 |
| Total of 120 Payments | $127,278.62 |
| Total Interest | $27,278.62 |
| All Payments and Fees | $128,278.62 |
| Real APR | 5.848% |
|---|---|
| Loan Amount | $280,000.00 |
| Down Payment | $70,000.00 |
| Monthly Pay | $3,038.74 |
| Total of 120 Payments | $364,648.80 |
| Total Interest | $84,648.13 |
| PMI Insurance (0 months) | $0.00/month |
| Total PMI Insurance Payments | $0.00 |
| All Payments and Fees | $367,648.80 |
Interest
Principal
Fees
| № | BEGINNING BALANCE | INTEREST | PRINCIPAL | ENDING BALANCE |
|---|---|---|---|---|
| 1 | $100,000.00 | $416.67 | $643.99 | $99,356.01 |
| 2 | $99,356.01 | $413.98 | $646.67 | $98,709.34 |
| 3 | $98,709.34 | $411.29 | $649.37 | $98,059.97 |
| 4 | $98,059.97 | $408.58 | $652.07 | $97,407.90 |
| 5 | $97,407.90 | $405.87 | $654.79 | $96,753.11 |
| 6 | $96,753.11 | $403.14 | $657.52 | $96,095.60 |
| 7 | $96,095.60 | $400.40 | $660.26 | $95,435.34 |
| 8 | $95,435.34 | $397.65 | $663.01 | $94,772.33 |
| 9 | $94,772.33 | $394.88 | $665.77 | $94,106.56 |
| 10 | $94,106.56 | $392.11 | $668.54 | $93,438.02 |
| 11 | $93,438.02 | $389.33 | $671.33 | $92,766.69 |
| 12 | $92,766.69 | $386.53 | $674.13 | $92,092.56 |
| 13 | $92,092.56 | $383.72 | $676.94 | $91,415.62 |
| 14 | $91,415.62 | $380.90 | $679.76 | $90,735.87 |
| 15 | $90,735.87 | $378.07 | $682.59 | $90,053.28 |
| 16 | $90,053.28 | $375.22 | $685.43 | $89,367.84 |
| 17 | $89,367.84 | $372.37 | $688.29 | $88,679.55 |
| 18 | $88,679.55 | $369.50 | $691.16 | $87,988.40 |
| 19 | $87,988.40 | $366.62 | $694.04 | $87,294.36 |
| 20 | $87,294.36 | $363.73 | $696.93 | $86,597.43 |
| 21 | $86,597.43 | $360.82 | $699.83 | $85,897.60 |
| 22 | $85,897.60 | $357.91 | $702.75 | $85,194.85 |
| 23 | $85,194.85 | $354.98 | $705.68 | $84,489.17 |
| 24 | $84,489.17 | $352.04 | $708.62 | $83,780.56 |
| 25 | $83,780.56 | $349.09 | $711.57 | $83,068.99 |
| 26 | $83,068.99 | $346.12 | $714.53 | $82,354.45 |
| 27 | $82,354.45 | $343.14 | $717.51 | $81,636.94 |
| 28 | $81,636.94 | $340.15 | $720.50 | $80,916.44 |
| 29 | $80,916.44 | $337.15 | $723.50 | $80,192.94 |
| 30 | $80,192.94 | $334.14 | $726.52 | $79,466.42 |
| 31 | $79,466.42 | $331.11 | $729.55 | $78,736.87 |
| 32 | $78,736.87 | $328.07 | $732.58 | $78,004.29 |
| 33 | $78,004.29 | $325.02 | $735.64 | $77,268.65 |
| 34 | $77,268.65 | $321.95 | $738.70 | $76,529.95 |
| 35 | $76,529.95 | $318.87 | $741.78 | $75,788.17 |
| 36 | $75,788.17 | $315.78 | $744.87 | $75,043.30 |
| 37 | $75,043.30 | $312.68 | $747.97 | $74,295.32 |
| 38 | $74,295.32 | $309.56 | $751.09 | $73,544.23 |
| 39 | $73,544.23 | $306.43 | $754.22 | $72,790.01 |
| 40 | $72,790.01 | $303.29 | $757.36 | $72,032.65 |
| 41 | $72,032.65 | $300.14 | $760.52 | $71,272.13 |
| 42 | $71,272.13 | $296.97 | $763.69 | $70,508.44 |
| 43 | $70,508.44 | $293.79 | $766.87 | $69,741.57 |
| 44 | $69,741.57 | $290.59 | $770.07 | $68,971.51 |
| 45 | $68,971.51 | $287.38 | $773.27 | $68,198.23 |
| 46 | $68,198.23 | $284.16 | $776.50 | $67,421.74 |
| 47 | $67,421.74 | $280.92 | $779.73 | $66,642.00 |
| 48 | $66,642.00 | $277.68 | $782.98 | $65,859.02 |
| 49 | $65,859.02 | $274.41 | $786.24 | $65,072.78 |
| 50 | $65,072.78 | $271.14 | $789.52 | $64,283.26 |
| 51 | $64,283.26 | $267.85 | $792.81 | $63,490.46 |
| 52 | $63,490.46 | $264.54 | $796.11 | $62,694.34 |
| 53 | $62,694.34 | $261.23 | $799.43 | $61,894.91 |
| 54 | $61,894.91 | $257.90 | $802.76 | $61,092.16 |
| 55 | $61,092.16 | $254.55 | $806.10 | $60,286.05 |
| 56 | $60,286.05 | $251.19 | $809.46 | $59,476.59 |
| 57 | $59,476.59 | $247.82 | $812.84 | $58,663.75 |
| 58 | $58,663.75 | $244.43 | $816.22 | $57,847.53 |
| 59 | $57,847.53 | $241.03 | $819.62 | $57,027.90 |
| 60 | $57,027.90 | $237.62 | $823.04 | $56,204.87 |
| 61 | $56,204.87 | $234.19 | $826.47 | $55,378.40 |
| 62 | $55,378.40 | $230.74 | $829.91 | $54,548.49 |
| 63 | $54,548.49 | $227.29 | $833.37 | $53,715.12 |
| 64 | $53,715.12 | $223.81 | $836.84 | $52,878.27 |
| 65 | $52,878.27 | $220.33 | $840.33 | $52,037.94 |
| 66 | $52,037.94 | $216.82 | $843.83 | $51,194.11 |
| 67 | $51,194.11 | $213.31 | $847.35 | $50,346.77 |
| 68 | $50,346.77 | $209.78 | $850.88 | $49,495.89 |
| 69 | $49,495.89 | $206.23 | $854.42 | $48,641.47 |
| 70 | $48,641.47 | $202.67 | $857.98 | $47,783.49 |
| 71 | $47,783.49 | $199.10 | $861.56 | $46,921.93 |
| 72 | $46,921.93 | $195.51 | $865.15 | $46,056.78 |
| 73 | $46,056.78 | $191.90 | $868.75 | $45,188.03 |
| 74 | $45,188.03 | $188.28 | $872.37 | $44,315.66 |
| 75 | $44,315.66 | $184.65 | $876.01 | $43,439.65 |
| 76 | $43,439.65 | $181.00 | $879.66 | $42,560.00 |
| 77 | $42,560.00 | $177.33 | $883.32 | $41,676.67 |
| 78 | $41,676.67 | $173.65 | $887.00 | $40,789.67 |
| 79 | $40,789.67 | $169.96 | $890.70 | $39,898.97 |
| 80 | $39,898.97 | $166.25 | $894.41 | $39,004.56 |
| 81 | $39,004.56 | $162.52 | $898.14 | $38,106.43 |
| 82 | $38,106.43 | $158.78 | $901.88 | $37,204.55 |
| 83 | $37,204.55 | $155.02 | $905.64 | $36,298.91 |
| 84 | $36,298.91 | $151.25 | $909.41 | $35,389.50 |
| 85 | $35,389.50 | $147.46 | $913.20 | $34,476.30 |
| 86 | $34,476.30 | $143.65 | $917.00 | $33,559.30 |
| 87 | $33,559.30 | $139.83 | $920.82 | $32,638.48 |
| 88 | $32,638.48 | $135.99 | $924.66 | $31,713.81 |
| 89 | $31,713.81 | $132.14 | $928.51 | $30,785.30 |
| 90 | $30,785.30 | $128.27 | $932.38 | $29,852.92 |
| 91 | $29,852.92 | $124.39 | $936.27 | $28,916.65 |
| 92 | $28,916.65 | $120.49 | $940.17 | $27,976.48 |
| 93 | $27,976.48 | $116.57 | $944.09 | $27,032.39 |
| 94 | $27,032.39 | $112.63 | $948.02 | $26,084.37 |
| 95 | $26,084.37 | $108.68 | $951.97 | $25,132.40 |
| 96 | $25,132.40 | $104.72 | $955.94 | $24,176.47 |
| 97 | $24,176.47 | $100.74 | $959.92 | $23,216.55 |
| 98 | $23,216.55 | $96.74 | $963.92 | $22,252.63 |
| 99 | $22,252.63 | $92.72 | $967.94 | $21,284.69 |
| 100 | $21,284.69 | $88.69 | $971.97 | $20,312.72 |
| 101 | $20,312.72 | $84.64 | $976.02 | $19,336.70 |
| 102 | $19,336.70 | $80.57 | $980.09 | $18,356.62 |
| 103 | $18,356.62 | $76.49 | $984.17 | $17,372.45 |
| 104 | $17,372.45 | $72.39 | $988.27 | $16,384.18 |
| 105 | $16,384.18 | $68.27 | $992.39 | $15,391.79 |
| 106 | $15,391.79 | $64.13 | $996.52 | $14,395.27 |
| 107 | $14,395.27 | $59.98 | $1,000.67 | $13,394.59 |
| 108 | $13,394.59 | $55.81 | $1,004.84 | $12,389.75 |
| 109 | $12,389.75 | $51.62 | $1,009.03 | $11,380.72 |
| 110 | $11,380.72 | $47.42 | $1,013.24 | $10,367.48 |
| 111 | $10,367.48 | $43.20 | $1,017.46 | $9,350.02 |
| 112 | $9,350.02 | $38.96 | $1,021.70 | $8,328.33 |
| 113 | $8,328.33 | $34.70 | $1,025.95 | $7,302.37 |
| 114 | $7,302.37 | $30.43 | $1,030.23 | $6,272.15 |
| 115 | $6,272.15 | $26.13 | $1,034.52 | $5,237.62 |
| 116 | $5,237.62 | $21.82 | $1,038.83 | $4,198.79 |
| 117 | $4,198.79 | $17.49 | $1,043.16 | $3,155.63 |
| 118 | $3,155.63 | $13.15 | $1,047.51 | $2,108.13 |
| 119 | $2,108.13 | $8.78 | $1,051.87 | $1,056.25 |
| 120 | $1,056.25 | $4.40 | $1,056.25 | $0.00 |
APR calculator at a glance#
What is the difference between APR and the interest rate?#
The interest rate is what the lender charges for the money you borrow. The APR, or annual percentage rate, is the interest rate plus the fees charged with the loan, such as origination charges, expressed as one yearly rate. When a loan has fees that count toward the APR, its APR is higher than its interest rate. The Consumer Financial Protection Bureau's advice is to compare APR to APR, never one loan's APR to another's interest rate.
How do you calculate APR on a loan?#
Work out the payment from the interest rate, then find the rate at which the money you actually receive would be repaid by those same payments. Take a $25,000 loan at an example rate of 7% for 5 years with a $750 upfront fee. The payment is $495.03 a month, but you only get $24,250 after the fee. The rate that turns $24,250 into 60 payments of $495.03 is 8.286%, and that's the APR. The calculator above does this search for you. This gives an estimate, not financial advice.
How much does a fee raise the APR?#
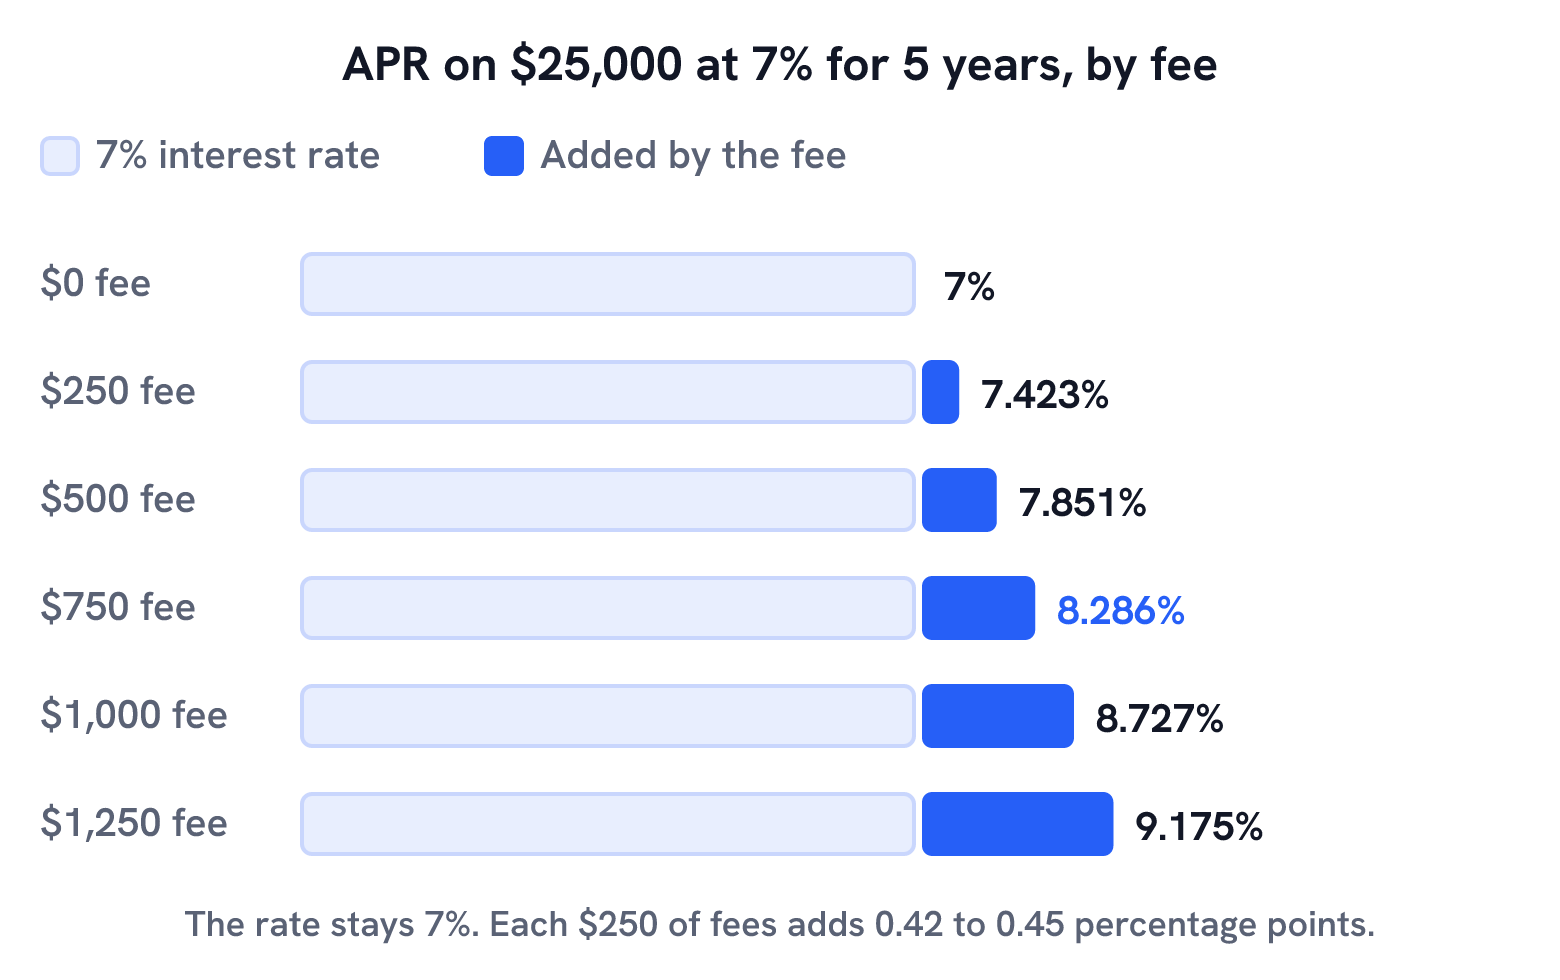
It depends on the fee and the term. On the 5-year example, each $250 of upfront fees adds 0.42 to 0.45 percentage points, so $750 lifts a 7% rate to 8.286%. The same $750 on a 2-year loan gives 10.027%, because the fee is spread over fewer payments.
What APR means under federal rules#
APR is a legal term, not just a lender's label. For most consumer loans, the Truth in Lending Act requires lenders to disclose it, and the CFPB's Regulation Z sets out how it's figured. Section 1026.22 describes the APR as a measure of the cost of credit, expressed as a yearly rate, that relates the amount and timing of value you receive to the amount and timing of the payments you make. For a regular loan, a disclosed APR counts as accurate if it's within one-eighth of a percentage point of the true figure.
The costs that go into it are the finance charge. Regulation Z's definition of the finance charge covers interest and any charge you pay as a condition of getting the credit, including:
- interest
- service, transaction and carrying charges
- points, loan fees, assumption fees and finder's fees
- appraisal, investigation and credit report fees, outside the mortgage exception below
- premiums for insurance that protects the lender against default
On a loan secured by real estate, some closing costs are left out of the finance charge if they're bona fide and reasonable: title fees, document preparation, notary fees, credit report fees and appraisal and inspection fees. Charges you'd pay in a cash purchase too, and late fees, aren't part of it either.
How the calculator works out APR#
The General APR tab takes the loan amount, the interest rate, the term in years and months, how often interest compounds and how often you pay, plus two kinds of fees:
- Upfront fees: fees you pay at closing or that come out of the loan, so you receive less than the loan amount.
- Loaned fees: fees added to the loan balance, so your payments are figured on the amount plus the fees.
It works out the payment from the interest rate, then searches for the rate at which the money you really receive (the loan amount minus upfront fees) is repaid by that payment schedule. That rate is shown as Real APR. The results also list a figure it labels Amount Financed (the loan amount plus any loaned fees), the upfront out-of-pocket fees, the payment, the total of payments, the total interest, all payments and fees, and an amortization schedule.
A worked example#
Here's the $25,000 loan at 7% for 5 years with a $750 fee paid up front:
- Monthly payment from the 7% rate: $495.03, from the standard formula explained with the loan calculator
- Total of 60 payments: $29,701.80, of which $4,701.80 is interest
- Money you really receive: $25,000 − $750 = $24,250
- Real APR, the rate that turns $24,250 into 60 payments of $495.03: 8.286%
The calculator finds that last number by trial: it tries a rate, checks whether the payment it implies on $24,250 is too high or too low, and narrows the range until it settles on 8.286%. There's no way to solve the payment formula for the rate directly, so the calculator narrows in on it step by step. With monthly payments, the calculator's APR is the monthly rate it finds times 12.
If the same $750 is added to the loan instead, the balance becomes $25,750 and the payment rises to $509.88. You still receive $25,000, and the APR comes out at 8.248%, close to the upfront version because the fee is a cost either way. With loaned fees, read Total of 60 Payments, $30,592.85 here, not All Payments and Fees, which shows $31,342.85 because it counts the loaned fee twice.
How the fee size and the term change APR#
Bigger fees push the APR up in near-equal steps. With no fee the APR equals the 7% interest rate. At $250 it's 7.423%, at $500 it's 7.851%, at $750 it's 8.286% and at $1,000 it's 8.727%.
The term matters as much as the fee. A fee is paid once, so on a short loan it weighs on fewer payments and raises the APR more:
- 2 years: payment $1,119.31, APR 10.027%
- 3 years: payment $771.93, APR 9.069%
- 5 years: payment $495.03, APR 8.286%
- 7 years: payment $377.32, APR 7.946%
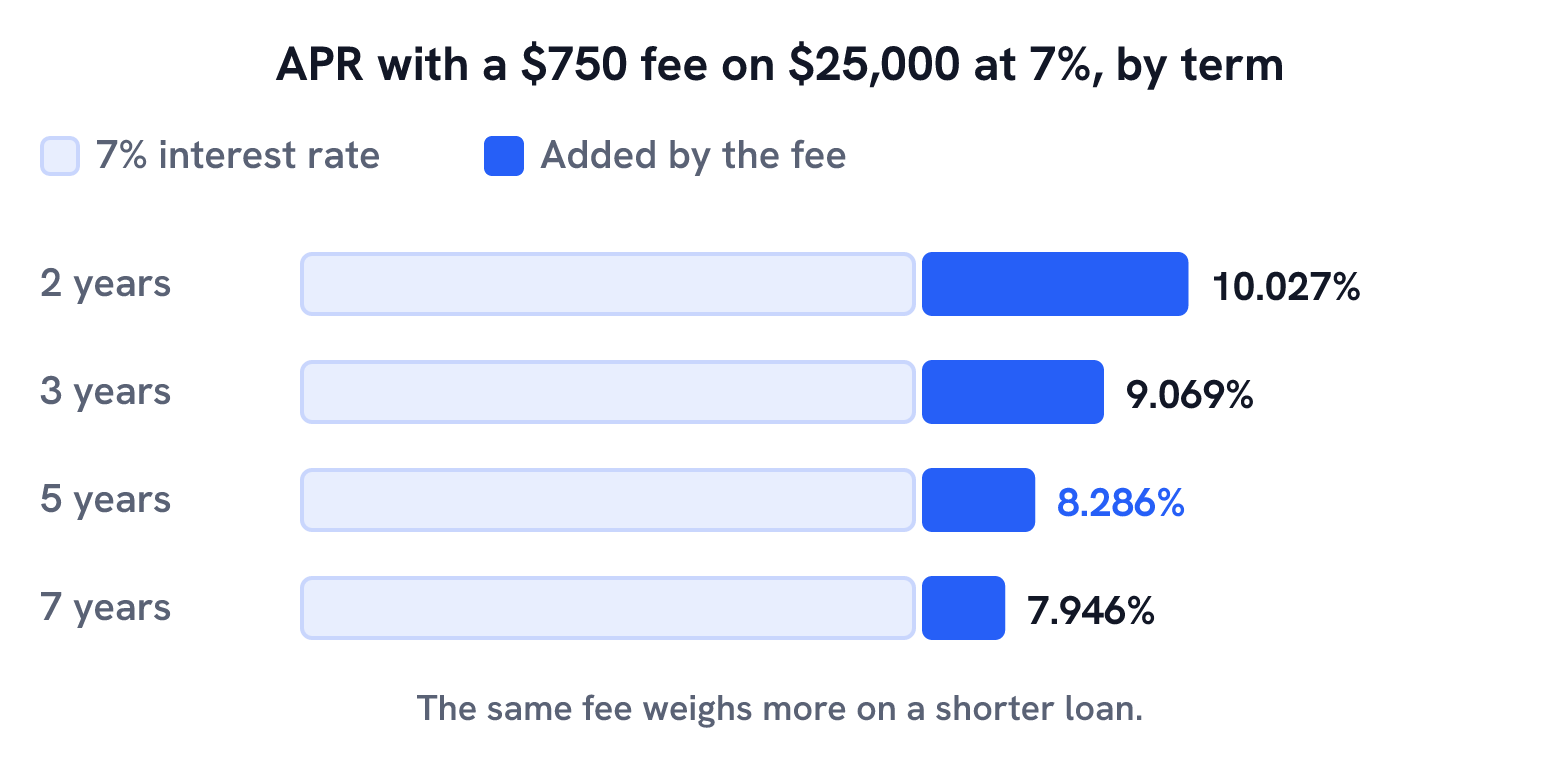
That's why APRs are most useful for comparing loans of the same length. A loan with a lower APR but a longer term can still cost more in total interest. The personal loan calculator page compares two offers side by side, and the business loan calculator gives the same kind of real rate for business loans with origination, documentation and other fees.
Mortgage APR#
The Mortgage APR tab takes the house value, the down payment as a percentage, the interest rate, the term in years, the loan fees, the points and PMI in dollars per year. One point is 1% of the loan amount. If the down payment is 20% or more, the calculator leaves PMI out. It returns the real APR along with the loan amount, the down payment, the monthly payment, the total of payments, the total interest and the PMI it expects you to pay.
For example, a $400,000 house with 20% down, at an example rate of 6.5% for 30 years, with $4,000 of loan fees and 1 point:
- Loan amount: $400,000 − $80,000 = $320,000
- One point: 1% of $320,000 = $3,200
- Monthly principal and interest: $2,022.62
- Real APR: 6.720%
Without the point the APR would be 6.621%, and with no fees at all it would equal the 6.5% rate. Regulation Z counts points and loan fees as part of the finance charge, so each one pushes the mortgage APR above the interest rate. Enter only fees that count as finance charges in Loan Fees. Title, appraisal, credit report and the other excluded closing costs would make the APR too high.
Sources#
- Consumer Financial Protection Bureau, What is the difference between a loan interest rate and the APR?
- Consumer Financial Protection Bureau, Regulation Z, 12 CFR 1026.22 Determination of annual percentage rate
- Consumer Financial Protection Bureau, Regulation Z, 12 CFR 1026.4 Finance charge
Frequently asked questions#
Why is my APR higher than my interest rate?#
Because the APR counts the loan's fees and the interest rate doesn't. If there are no fees, the two are the same. In the example, a $750 fee on a $25,000 loan at 7% for 5 years makes the APR 8.286%.
How do you turn an APR into a monthly rate?#
Divide by 12. A 7% APR on a loan with monthly payments is about 0.583% a month. Going the other way, the calculator's APR is the monthly rate it finds times 12.
Can I convert an APR back into an interest rate?#
Not without knowing the fees and the term. The APR mixes the two, so the same APR can come from a low rate with high fees or a higher rate with none. Ask the lender for both numbers. On most consumer loans, the lender has to disclose the APR under the Truth in Lending Act.
Does this calculator work for credit cards?#
No. It's built for installment loans with a set term and regular payments. A credit card's APR applies to a revolving balance with no fixed term, which this calculator doesn't model.
Which fees count toward APR?#
Under Regulation Z, interest, points, loan fees, finder's fees and insurance that protects the lender against default count. On a mortgage, bona fide and reasonable title, appraisal, credit report and similar fees are left out. Late fees don't count either.
Related calculators
View all calculators Investment CalculatorInvestment calculator: see what a starting amount plus monthly or yearly contributions grows to, or solve for the contribution, rate or time needed.
 Loan CalculatorLoan calculator: get the monthly payment, total interest and amortization schedule for any loan amount, rate and term, with a payment table by amount.
 Mortgage CalculatorMortgage calculator: estimate principal and interest from price, down payment, rate and term, with taxes, insurance, PMI and HOA in the total cost.
 Mortgage Payment CalculatorMortgage payment calculator: find the monthly principal and interest payment and see how an extra monthly payment shortens the loan and cuts interest.
 Payment CalculatorPayment calculator: find the monthly payment on a fixed-rate loan, or how long a set monthly payment takes to pay it off, with worked formula examples.
 Personal Loan CalculatorPersonal loan calculator: find the monthly payment, total interest and payoff date for any amount, rate and term, and learn how fees change the real cost.